Data Center Battery Market Size, Share, Trends & Growth Opportunities Forecast to 2026 - 2035
Data Center Battery Market Size, Share & Trends Report, 2026–2035
LAST UPDATED: OCTOBER 2026
The global data center battery market size was valued at USD 3,587.4 million in 2025 and is projected to reach USD 6,012.6 million by 2035, growing at a CAGR of 5.3% from 2026 to 2035. The market is estimated at USD 3,777.5 million in 2026, with North America holding the largest share and Asia Pacific registering the fastest growth.
Data center batteries are the energy storage systems that keep servers, storage and network equipment running when grid power fails or fluctuates. They sit mainly inside uninterruptible power supply (UPS) systems, providing the minutes of power needed until backup generators start, and are increasingly used in battery energy storage systems (BESS) for peak shaving, load balancing and grid services.
The market is going through a major technology shift. Valve-regulated lead-acid (VRLA) batteries still make up the largest installed base, but operators are moving to lithium-ion, mostly lithium iron phosphate (LFP), for its longer life, smaller footprint and lower total cost of ownership. At the same time, AI training clusters with sharp, fast-changing power demand are turning batteries from passive backup into active power management assets.
Data Center Battery Market Key Takeaways
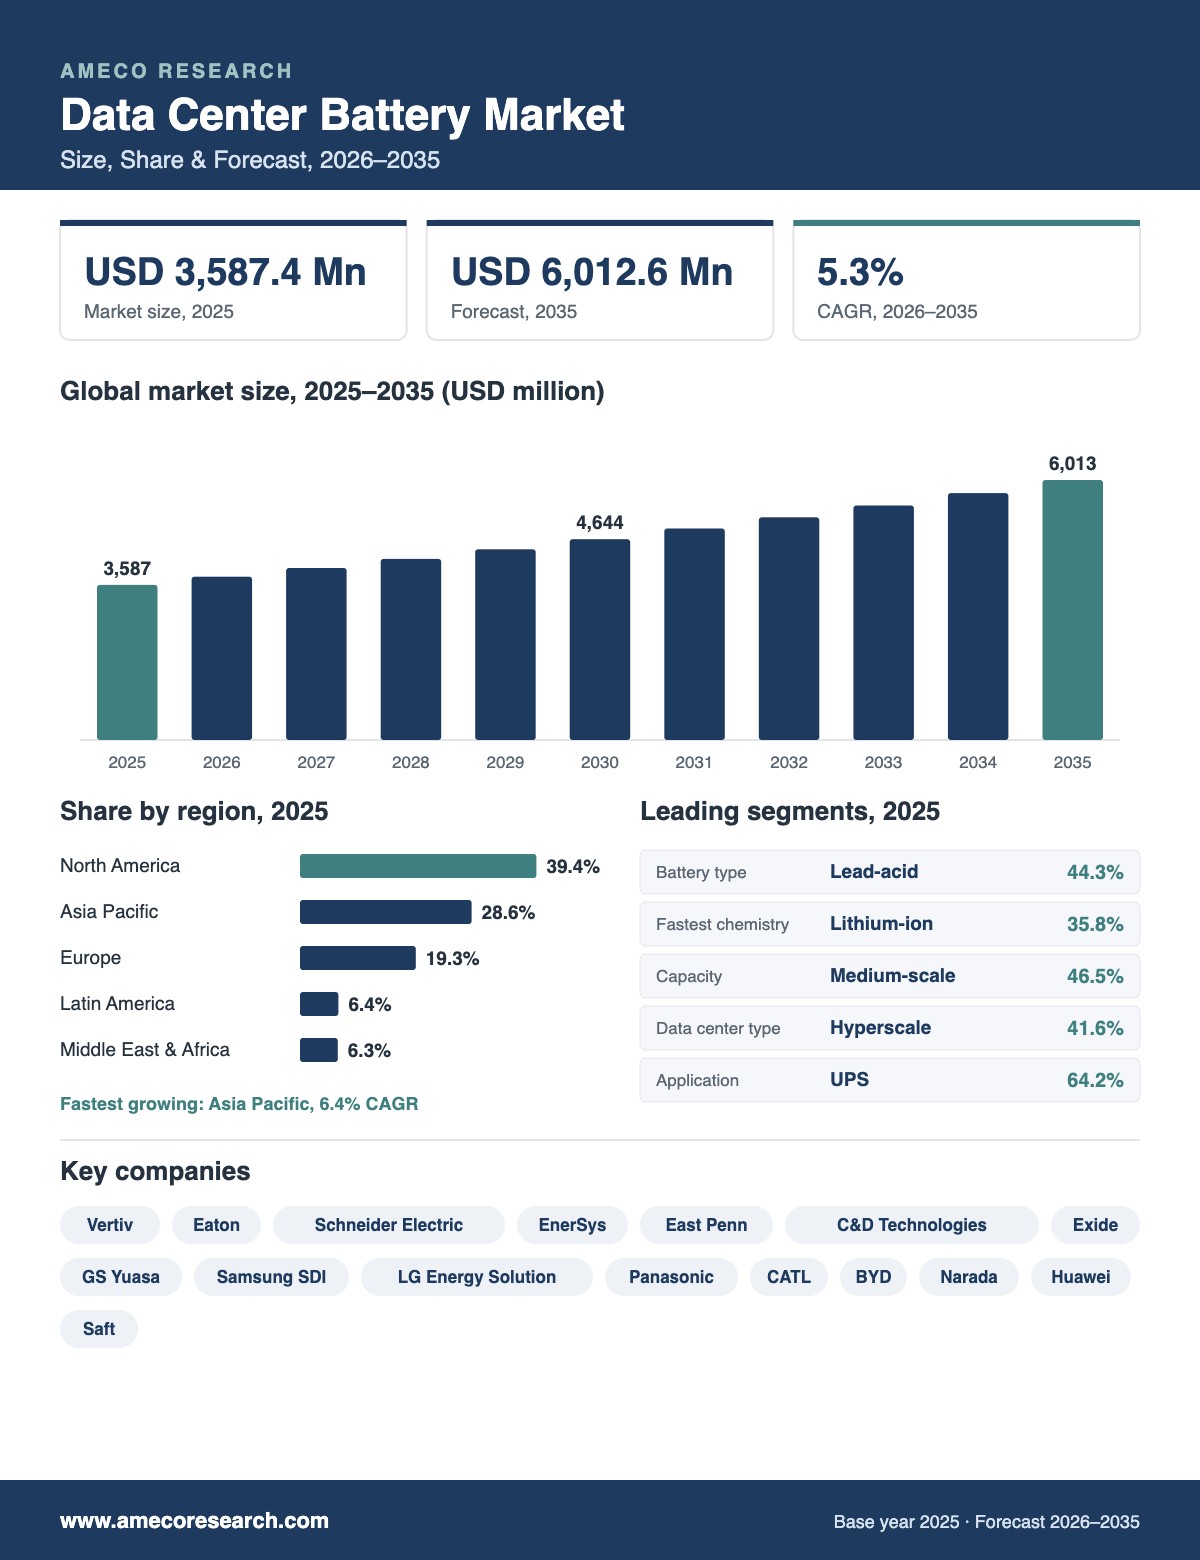 Infographic: Data Center Battery Market Size, Share, Trends & Growth Opportunities Forecast to 2026 - 2035 | Ameco Research
Data Center Battery Market Report Scope
| Report Attribute | Details |
| Data Center Battery Market Size in 2025 | USD 3,587.4 Million |
| Data Center Battery Market Size in 2026 | USD 3,777.5 Million |
| Data Center Battery Market Forecast by 2035 | USD 6,012.6 Million |
| Data Center Battery Market CAGR (2026–2035) | 5.3% |
| Historical Data | 2021–2024 |
| Base Year | 2025 |
| Forecast Period | 2026–2035 |
| Largest Region | North America (39.4% share in 2025) |
| Fastest-Growing Region | Asia Pacific (6.4% CAGR) |
| Segments Covered | Battery Type, Battery Capacity, Data Center Type, Application and Region |
| Regional Scope | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
| Key Companies Profiled | Vertiv, Eaton, Schneider Electric, EnerSys, East Penn Manufacturing, C&D Technologies, Exide Technologies, GS Yuasa, Samsung SDI, LG Energy Solution, Panasonic, CATL, BYD, Narada Power, Huawei Digital Power and Saft (TotalEnergies) |
| Report Coverage | Market size and forecast, trends, drivers, restraints, opportunities, segment and regional analysis, competitive landscape, recent developments |
How Big Is the Data Center Battery Market in 2026?
Ameco Research estimates the data center battery market at USD 3,777.5 million in 2026, up from USD 3,587.4 million in 2025. The market is expected to reach about USD 4,644.3 million by 2030 and USD 6,012.6 million by 2035. Battery volumes are growing much faster than revenue, because lithium-ion cell prices have fallen sharply and each lithium-ion system replaces several generations of shorter-lived lead-acid batteries.
| Year | Data Center Battery Market Size (USD Million) |
| 2025 | 3,587.4 |
| 2026 | 3,777.5 |
| 2028 | 4,188.6 |
| 2030 | 4,644.3 |
| 2032 | 5,149.7 |
| 2035 | 6,012.6 |
Latest Data Center Battery Market Trends 2026
Lithium-ion replaces lead-acid in new builds
Most new hyperscale and colocation halls now specify lithium-ion UPS batteries, mainly LFP, which offer 10–15 year lifespans, 50–70% smaller footprints and lower cooling needs than VRLA. Lead-acid remains common in retrofits and smaller enterprise sites because of its lower upfront cost.
AI workloads turn batteries into power managers
AI training clusters can swing power demand by tens of megawatts in seconds. Batteries now smooth these swings, protect GPUs and stabilize the grid connection. Fastmarkets estimates that energy storage linked to AI data centers could reach about 300 GWh of demand by 2030.
Medium-voltage UPS and grid ride-through
New medium-voltage UPS systems use battery storage to ride through grid faults instead of disconnecting, a requirement increasingly asked for by utilities. Around 3 GW of such projects are in operation or under construction in the U.S., according to developer ON.energy.
Battery storage as a bridge to grid power
Long waits for grid connections are pushing operators to install large battery energy storage systems on site. In August 2026, Cummins won its largest BESS contract, a 5 MWh LFP system for a U.S. data center that helps manage AI load swings and offers a quieter, zero-emission alternative to diesel generators.
Falling LFP cell prices
Large-format 314Ah LFP prismatic cells were trading around USD 0.05 per Wh in mid-2026, making lithium-ion storage cost-competitive with lead-acid on a lifetime basis and enabling larger battery systems for peak shaving and demand response.
Second-life and new chemistries
Repurposed EV batteries and sodium-ion cells are emerging as lower-cost options. In May 2026, Cleantech Energy Company raised USD 40 million to scale energy storage systems built from second-life EV batteries for data centers.
Data Center Battery Market Dynamics
Growth drivers
- Data center construction boom: cloud computing, AI, streaming and digital services are driving record hyperscale and colocation capacity additions, all of which need battery backup.
- Zero-downtime requirements: outages can cost operators hundreds of thousands of dollars per hour, so reliable UPS batteries are essential for Tier III and Tier IV facilities.
- AI and high-density computing: GPU racks need stable, clean power and fast response to grid disturbances and rapid load changes.
- Replacement of aging lead-acid fleets: short VRLA lifespans create a steady replacement cycle, much of which now shifts to lithium-ion.
- Renewable energy and grid services: batteries help data centers use more solar and wind power, shave peak demand and earn revenue from grid support programs.
Restraints and challenges
- High upfront cost of lithium-ion: lithium-ion systems, battery management and monitoring cost more initially, which can deter small and mid-sized operators.
- Fire safety and regulation: lithium-ion installations must meet standards such as UL 9540A and NFPA 855, adding design, testing and insurance requirements.
- Retrofit complexity: moving from lead-acid to lithium-ion may require changes to UPS, cooling and safety systems in existing halls.
- Supply chain risks: dependence on lithium, graphite and cell manufacturing in a few countries exposes buyers to price swings and trade restrictions.
- Recycling and end-of-life: growing battery volumes require recycling and disposal solutions, especially for lithium-ion.
Opportunities
- Grid-interactive UPS that lets data centers sell frequency regulation and demand response services to utilities.
- Large-scale BESS for AI campuses to bridge delayed grid connections and replace part of diesel generator capacity.
- Renewable integration as operators such as Google and Microsoft pursue 24/7 carbon-free energy goals.
- Sodium-ion and second-life batteries offering lower-cost, safer storage for backup applications.
- Edge data centers needing compact, maintenance-free lithium-ion backup in remote and urban sites.
Data Center Battery Market Segment Analysis
By battery type: Is lithium-ion overtaking lead-acid in data centers?
Lead-acid batteries, mainly VRLA, accounted for 44.3% of revenue in 2025 because of their low upfront cost and large installed base. Lithium-ion held 35.8% and is the fastest-growing chemistry, expected to become the largest segment within the forecast period as new hyperscale and colocation sites standardize on LFP.
| Battery Type | Share (2025) | Key Highlights |
| Lead-Acid (VRLA) | 44.3% | Lowest upfront cost; large installed base; 3–6 year life |
| Lithium-Ion | 35.8% | Fastest-growing; 10–15 year life; smaller footprint |
| Nickel-Based (NiZn, NiCd) | 12.4% | High power density and wide temperature tolerance |
| Others (Sodium-Ion, Flow) | 7.5% | Emerging low-cost and long-duration options |
By battery capacity
Medium-scale batteries held the largest share at 46.5% in 2025, serving typical enterprise and colocation UPS systems. Small-scale batteries accounted for 42.6%, used in server rooms, edge sites and rack-level UPS. Large-scale systems held 10.9% but are the fastest-growing capacity segment as hyperscale and AI campuses add megawatt-scale battery energy storage.
| Battery Capacity | Share (2025) | Key Highlights |
| Small-Scale | 42.6% | Rack and room UPS for edge and small enterprise sites |
| Medium-Scale | 46.5% | Largest segment; central UPS in enterprise and colocation |
| Large-Scale | 10.9% | Fastest-growing; MW-scale BESS for hyperscale and AI campuses |
By data center type: Why do hyperscale facilities lead?
Hyperscale data centers accounted for 41.6% of demand in 2025, as cloud and AI providers build very large campuses with high battery requirements and are early adopters of lithium-ion. Colocation held 26.5%, enterprise 21.4% and edge 10.5%.
| Data Center Type | Share (2025) | Key Highlights |
| Hyperscale | 41.6% | Largest buyers; cloud and AI campuses standardizing on LFP |
| Colocation | 26.5% | Multi-tenant facilities with strict uptime SLAs |
| Enterprise | 21.4% | On-premises sites; many still on lead-acid |
| Edge | 10.5% | Compact, maintenance-free backup for distributed sites |
By application
Uninterruptible power supply (UPS) systems accounted for 64.2% of revenue in 2025, as nearly every data center relies on UPS batteries to bridge the seconds to minutes before generators start. Backup power systems held 20.6%, while energy storage, peak shaving and load balancing applications held 15.2% and are growing fastest.
| Application | Share (2025) | Key Highlights |
| Uninterruptible Power Supply (UPS) | 64.2% | Core application; bridges power until generators start |
| Backup Power Systems | 20.6% | Extended runtime for critical loads and generator support |
| Energy Storage, Peak Shaving & Load Balancing | 15.2% | Fastest-growing; grid services and AI load smoothing |
Data Center Battery Market Regional Analysis
| Region | Share (2025) | Outlook |
| North America | 39.4% | Largest market; U.S. hyperscale and AI campus construction |
| Asia Pacific | 28.6% | Fastest-growing at a 6.4% CAGR; China, India, Japan, Singapore |
| Europe | 19.3% | Germany, U.K., Ireland, Netherlands and Nordics; sustainability rules |
| Latin America | 6.4% | New capacity in Brazil, Mexico and Chile |
| Middle East & Africa | 6.3% | Gulf AI campuses and South African data center hubs |
Why does North America dominate the data center battery market?
North America accounted for about 39.4% of global revenue in 2025. The United States hosts the largest concentration of hyperscale and AI data centers, in markets such as Northern Virginia, Texas, Arizona, Ohio and California, and operators such as AWS, Microsoft, Google and Meta are rapidly adopting lithium-ion UPS and on-site battery storage. Federal energy storage tax credits and grid connection delays further support large battery deployments.
What makes Asia Pacific the fastest-growing region?
Asia Pacific held about 28.6% of the market in 2025 and is expected to grow at a 6.4% CAGR through 2035. China is the largest regional market and home to major battery makers such as CATL, BYD and Narada, while India, Japan, Singapore, Malaysia and Australia are adding large amounts of new data center capacity.
How is Europe developing?
Europe represented about 19.3% of revenue in 2025. EU sustainability and energy efficiency rules, high electricity prices and the push for renewable power are encouraging operators in Germany, the U.K., Ireland, the Netherlands and the Nordics to deploy lithium-ion batteries that can also provide grid balancing services.
Data Center Battery Market Segmentation
Data Center Battery Market Leading Companies
The data center battery market includes UPS and power infrastructure suppliers, established lead-acid battery manufacturers and large lithium-ion cell makers. Competition centers on battery life, energy density, safety certification, total cost of ownership, monitoring software and the ability to supply complete battery cabinets and energy storage systems for large campuses.
Vertiv · Eaton · Schneider Electric · EnerSys · East Penn Manufacturing · C&D Technologies · Exide Technologies · GS Yuasa · Samsung SDI · LG Energy Solution · Panasonic · CATL · BYD · Narada Power · Huawei Digital Power · Saft (TotalEnergies)
Recent developments
- August 2026: Cummins secured its largest battery energy storage contract to date, a 5 MWh lithium iron phosphate system for a large U.S. data center project, designed to manage AI-driven load swings and support bridge-to-grid operation.
- July 2026: Fastmarkets reported that medium-voltage UPS systems at AI data centers are becoming a significant new source of LFP cell demand, estimating AI data center-linked storage demand could reach about 300 GWh by 2030.
- May 2026: Cleantech Energy Company raised USD 40 million to scale production of energy storage systems made from repurposed EV batteries for data centers.
Data Center Battery Market: Frequently Asked Questions
How big is the data center battery market?
The global data center battery market was valued at USD 3,587.4 million in 2025 and is estimated at USD 3,777.5 million in 2026. Ameco Research projects it to reach USD 6,012.6 million by 2035, growing at a CAGR of 5.3% from 2026 to 2035.
What is the growth rate of the data center battery market?
The market is expected to grow at a CAGR of 5.3% between 2026 and 2035. Value growth is steady because falling lithium-ion prices offset rising battery volumes, while the shift from lead-acid to lithium-ion and new uses such as grid support and peak shaving add demand.
What batteries are used in data centers?
Data centers mainly use valve-regulated lead-acid (VRLA) batteries and lithium-ion batteries, usually lithium iron phosphate (LFP), inside uninterruptible power supply (UPS) systems. Nickel-based batteries such as nickel-zinc and nickel-cadmium, and newer chemistries such as sodium-ion, are used in smaller numbers. Lead-acid held about 44.3% of revenue in 2025 and lithium-ion about 35.8%.
Why are data centers switching from lead-acid to lithium-ion batteries?
Lithium-ion batteries last about 10–15 years versus 3–6 years for VRLA, take up roughly 50–70% less space, weigh much less and need less cooling. Although they cost more upfront, they usually have a lower total cost of ownership and can support new functions such as peak shaving and grid services.
How long do data center UPS batteries last?
VRLA lead-acid UPS batteries typically last 3–6 years in data center service, while lithium-ion UPS batteries are commonly rated for 10–15 years. Most UPS batteries are sized to provide 5–15 minutes of runtime, enough to bridge the gap until backup generators start.
What is the role of batteries in AI data centers?
AI training clusters cause fast, large swings in power demand. Batteries smooth these swings, protect GPUs from grid disturbances and help sites ride through faults without disconnecting. Medium-voltage UPS and battery energy storage systems are increasingly installed at AI campuses for this purpose.
Which region leads the data center battery market?
North America leads with about 39.4% of global revenue in 2025, driven by hyperscale and AI data center construction in the U.S. Asia Pacific is the fastest-growing region at about a 6.4% CAGR, led by China, India, Japan and Southeast Asia.
Who are the key players in the data center battery market?
Leading companies include Vertiv, Eaton, Schneider Electric, EnerSys, East Penn Manufacturing, C&D Technologies, Exide Technologies, GS Yuasa, Samsung SDI, LG Energy Solution, Panasonic, CATL, BYD, Narada Power, Huawei Digital Power and Saft (TotalEnergies).
Related Energy and Power Market Reports
- Biogas Market Growth Opportunities and Forecast till 2032
- Mobile Generators Market Growth Opportunities and Forecast till 2032
- Residual Gas Analyzers Market Growth Opportunities and Forecast till 2032
- Small Hydropower Market Growth Opportunities and Forecast till 2032
- District Heating and Cooling Market Growth Opportunities and Forecast till 2032