Aerospace and Defense C-Class Parts Market Size and Growth Opportunities and Forecast till 2026 - 2035
Aerospace and Defense C-Class Parts Market Size, Share & Trends Report, 2026–2035
LAST UPDATED: OCTOBER 2026
The global Aerospace and Defense C-Class Parts Market size was valued at USD 20,225.1 million in 2025 and is projected to reach USD 31,409.0 million by 2035, growing at a CAGR of 4.5% from 2026 to 2035. Growth is driven by rising commercial aircraft production rates and record order backlogs, higher defense spending, fleet replacement with fuel-efficient aircraft, aftermarket maintenance demand, and supply chain programs that secure fasteners, bearings and electrical components.
Aerospace and defense C-class parts are low-cost, high-volume components such as fasteners (bolts, nuts, rivets, screws, washers), bearings, springs, clips, electrical connectors and small machined parts. Although each part has low unit value, aircraft and defense systems use them in very large quantities, and they must meet strict quality, traceability and certification standards. C-class parts are often supplied through kitting, vendor-managed inventory and distribution programs.
Aerospace and Defense C-Class Parts Market Key Takeaways
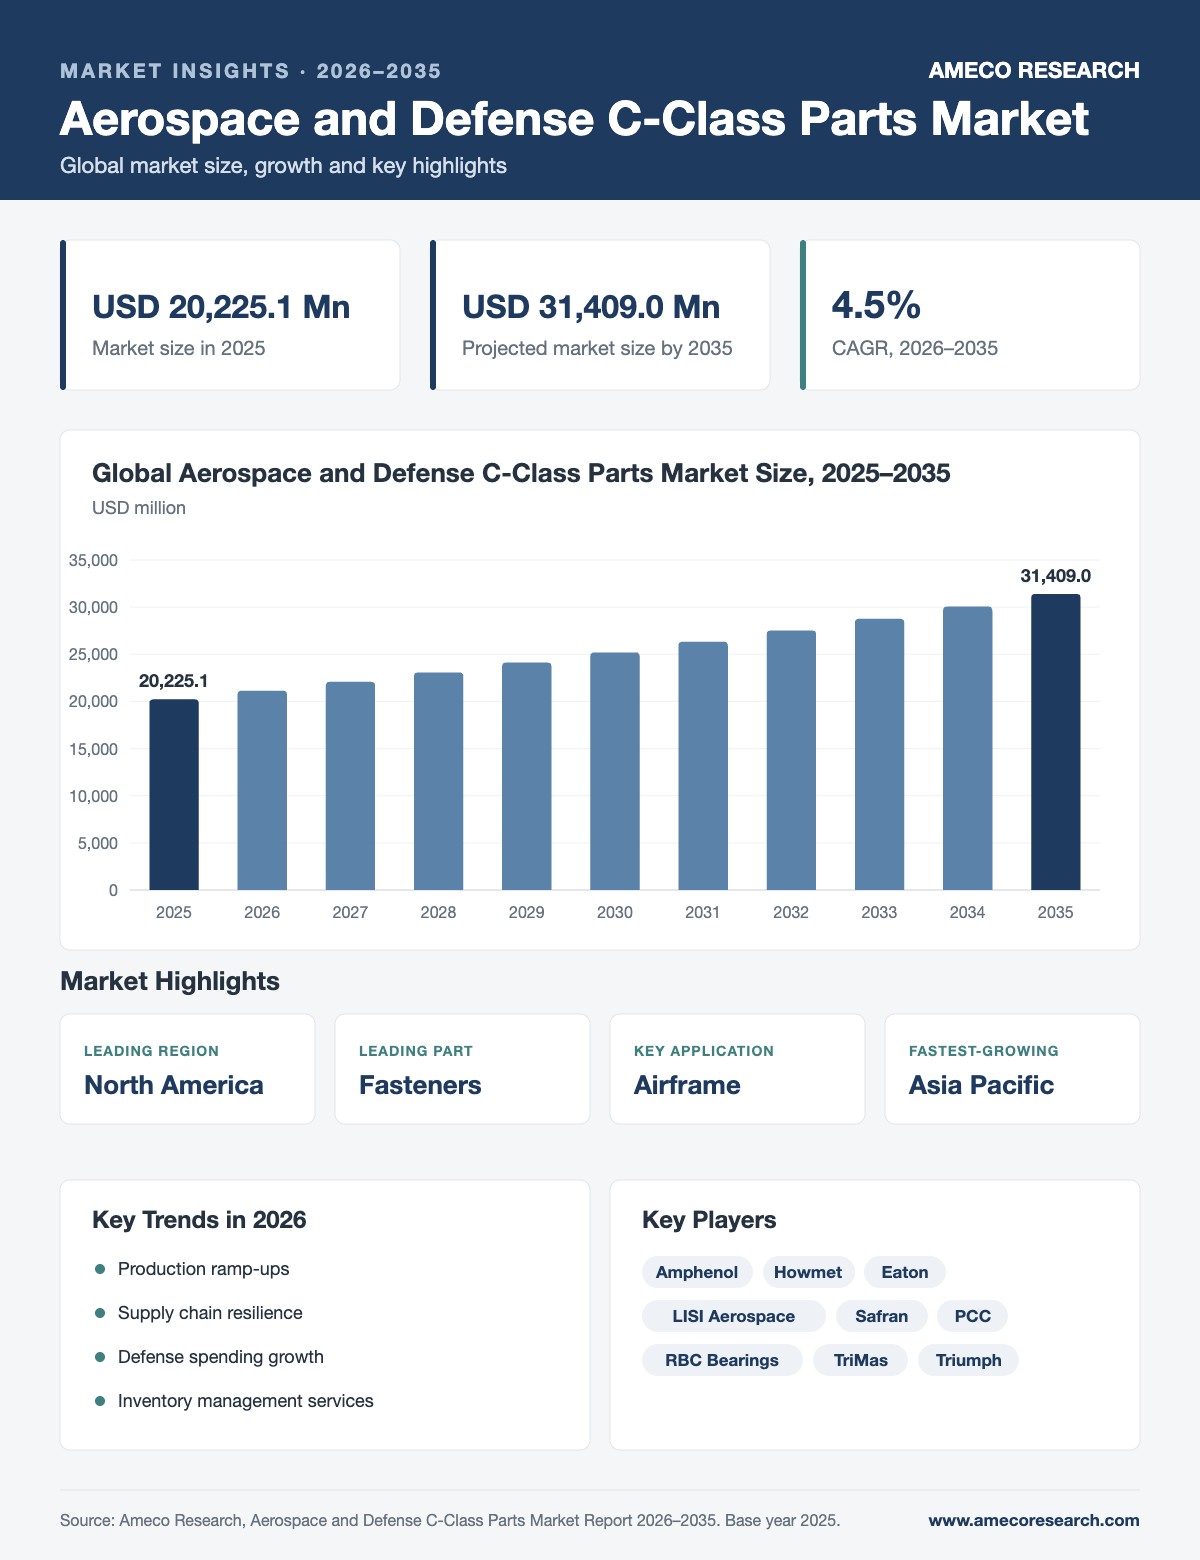 Infographic: Aerospace and Defense C-Class Parts Market Size and Growth Opportunities and Forecast till 2026 - 2035 | Ameco Research
Aerospace and Defense C-Class Parts Market Report Scope
| Report Attribute | Details |
| Aerospace and Defense C-Class Parts Market Size in 2025 | USD 20,225.1 Million |
| Aerospace and Defense C-Class Parts Market Forecast by 2035 | USD 31,409.0 Million |
| Aerospace and Defense C-Class Parts Market CAGR (2026–2035) | 4.5% |
| Analysis Period | 2023–2035 |
| Base Year | 2025 |
| Forecast Period | 2026–2035 |
| Segments Covered | by Part, by Application, by End Use, and By Region |
| Regional Scope | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
| Key Companies Profiled | Amphenol Corp., Arconic (Howmet Aerospace), Eaton Corp., LMI Aerospace, Inc., TriMas Corp., RBC Bearings, Inc., Precision Castparts Corp., LISI Aerospace, Safran SA, and Triumph Group |
| Report Coverage | Market Trends, Drivers, Restraints, Opportunities, Competitive Analysis, Player Profiling, Regulation Analysis |
Aerospace and Defense C-Class Parts Market Size Forecast, 2023–2035
Figures for 2025–2035 extend the earlier 2021 baseline of USD 16,960 million at the report's 4.5% CAGR.
| Year | Market Size (USD Million) |
| 2023 (historical) | 18,520.7 |
| 2024 (historical) | 19,354.2 |
| 2025 (base year) | 20,225.1 |
| 2026 (forecast) | 21,135.2 |
| 2027 (forecast) | 22,086.3 |
| 2028 (forecast) | 23,080.2 |
| 2029 (forecast) | 24,118.8 |
| 2030 (forecast) | 25,204.2 |
| 2031 (forecast) | 26,338.4 |
| 2032 (forecast) | 27,523.6 |
| 2033 (forecast) | 28,762.2 |
| 2034 (forecast) | 30,056.5 |
| 2035 (forecast) | 31,409.0 |
Latest Aerospace and Defense C-Class Parts Market Trends (2026)
Commercial production ramp-ups
Aircraft makers are working to raise production rates to meet large order backlogs for narrow-body and wide-body aircraft, increasing demand for fasteners, bearings and machined parts across the supply chain.
Supply chain resilience
Shortages of parts, materials and skilled labor have delayed aircraft deliveries, leading OEMs and Tier 1 suppliers to secure long-term contracts, dual sourcing and higher safety stocks for critical C-class parts.
Higher defense spending
Increased defense budgets in North America, Europe and Asia Pacific support production of fighter jets, helicopters, missiles and military vehicles, all of which use large numbers of certified small parts.
Inventory management and kitting
Distributors provide vendor-managed inventory, kitting and point-of-use supply so manufacturers can manage thousands of part numbers efficiently and avoid production stoppages.
Aftermarket and MRO demand
Older aircraft flying longer and high fleet utilization increase maintenance demand for replacement fasteners, bearings and electrical components.
Lightweight and advanced materials
Titanium and high-strength alloy fasteners and composite-compatible parts are needed for new fuel-efficient aircraft, adding value per part.
Aerospace and Defense C-Class Parts Market Dynamics
Growth drivers
- Demand for new aircraft to replace aging commercial and defense fleets
- Airline demand for fuel-efficient aircraft
- Growth of global air travel and airline fleets
- Higher defense spending worldwide
- Demand for reliable, certified parts from aircraft manufacturers
Restraints and challenges
- Supply chain disruptions and raw material shortages
- Strict certification and traceability requirements
- Risk of unreliable or counterfeit suppliers
- Availability of product substitutes and price pressure
Opportunities
Key opportunities include long-term supply agreements with OEMs, inventory management and kitting services, titanium and lightweight fasteners, MRO aftermarket supply, and aerospace manufacturing growth in India and other Asia Pacific countries.
Aerospace and Defense C-Class Parts Market Segment Analysis
By part
The market is segmented into fasteners, bearings, electrical and machined parts. Fasteners hold the largest share and are expected to stay in the lead, as aircraft use very large numbers of bolts, nuts, rivets and screws.
By application
Applications include interiors, airframe, engine and systems. Airframe is expected to show strong growth, linked to production of single-aisle and wide-body aircraft programs.
By end use
End uses include military, commercial, business & general aviation and others. Commercial aviation holds a significant share, while the military segment is expected to grow substantially with higher defense spending.
Aerospace and Defense C-Class Parts Market Regional Analysis
North America accounts for a significant portion of the market, supported by its established aircraft manufacturing and defense industries and a large share of the world's operational fleet.
Europe is a major market with large aircraft and engine manufacturing in France, Germany, the U.K. and Spain. Asia Pacific is expected to grow fastest, driven by fleet growth, defense spending and expanding aerospace manufacturing.
Latin America and the Middle East & Africa are smaller markets, supported by regional aircraft production, MRO and defense programs.
Aerospace and Defense C-Class Parts Market Segmentation
Aerospace and Defense C-Class Parts Market Leading Companies
The aerospace and defense C-class parts market includes fastener and bearing manufacturers, electrical component makers, machined parts suppliers and aerospace distributors. Companies compete on certification, quality, traceability, delivery reliability, price and inventory management services. Key players profiled in this report include Amphenol Corp., Arconic (Howmet Aerospace), Eaton Corp., LMI Aerospace, Inc., TriMas Corp., RBC Bearings, Inc., Precision Castparts Corp., LISI Aerospace, Safran SA, and Triumph Group.
Amphenol Corp.Arconic (Howmet Aerospace)Eaton Corp.LMI Aerospace, Inc.TriMas Corp.RBC Bearings, Inc.Precision Castparts Corp.LISI AerospaceSafran SATriumph Group
Key Questions Answered in This Report
- What is the size of the aerospace and defense c-class parts market in 2025, and how large will it be by 2030 and 2035?
- What are the main growth drivers, restraints and opportunities through 2035?
- Which by part and by application segments will grow the fastest?
- Which regions and countries offer the largest and fastest-growing opportunities?
- How are aircraft production ramp-ups, supply chain resilience and defense spending shaping C-class parts demand in 2026?
- Who are the leading companies, and what strategies are they using to compete?
Research Methodology
Ameco Research built this forecast from a mix of primary and secondary research. Analysts spoke with parts manufacturers, aircraft OEMs and Tier 1 suppliers, distributors and defense agencies to validate pricing, volumes and demand trends, and reviewed company filings, trade statistics, regulatory documents and industry publications. The aerospace and defense c-class parts market size was estimated with bottom-up and top-down approaches and validated through data triangulation, with 2025 as the base year and forecasts for 2026–2035.
Related Reports
- Materials Informatics Market Size - Global Industry Analysis, Market Size, Opportunities and Forecas... Report
- Homogenous Precious Metal Catalyst Market - Size, Industry Trends, Competitive Landscape, and Opport... Report
- Automation Software Market Report
- Automotive Electric HVAC Compressor Market Report
- 5G in Defense Market Report
Aerospace and Defense C-Class Parts Market: Frequently Asked Questions
How big is the aerospace and defense c-class parts market?
The global aerospace and defense c-class parts market was valued at USD 20,225.1 million in 2025 and is expected to reach USD 31,409.0 million by 2035.
What is the growth rate of the aerospace and defense c-class parts market?
The aerospace and defense c-class parts market is projected to grow at a CAGR of 4.5% from 2026 to 2035.
What will the aerospace and defense c-class parts market be worth in 2030?
The aerospace and defense c-class parts market is projected to reach about USD 25,204.2 million in 2030, growing at a CAGR of 4.5%.
What is driving growth in the aerospace and defense c-class parts market?
Key drivers are demand for new aircraft to replace aging fleets, fuel-efficient aircraft, growing air travel, higher defense spending and the need for reliable certified parts.
What is aerospace and defense c-class parts?
Aerospace and defense C-class parts are low-cost, high-volume components such as fasteners, bearings, electrical connectors and small machined parts used in aircraft and defense systems.
Which region leads the aerospace and defense c-class parts market?
North America accounts for a significant portion of the market, while Asia Pacific is expected to grow fastest.
Which segment holds the largest share of the aerospace and defense c-class parts market?
Fasteners hold the largest part share, and airframe is expected to show strong application growth.
What are the latest trends in the aerospace and defense c-class parts market?
The main 2026 trends are commercial production ramp-ups, supply chain resilience, higher defense spending, inventory management and kitting, aftermarket and MRO demand and lightweight and advanced materials.
What are the main challenges in the aerospace and defense c-class parts market?
The main challenges are supply chain disruptions, strict certification requirements, the risk of unreliable suppliers and price pressure from substitutes.
Why are C-class parts important in aerospace?
Although each part is low cost, aircraft need thousands of them, and a shortage of a single certified fastener or bearing can stop production or delay maintenance.
Who are the key players in the aerospace and defense c-class parts market?
Leading companies include Amphenol Corp., Arconic (Howmet Aerospace), Eaton Corp., LMI Aerospace, Inc., TriMas Corp., RBC Bearings, Inc., Precision Castparts Corp., LISI Aerospace, Safran SA, and Triumph Group.
Related Chemical & Material Market Reports
- Materials Informatics Market Size and Growth Opportunities and Forecast till 2026 - 2035
- Mandelic Acid Market Size and Growth Opportunities and Forecast till 2026 - 2035
- Refractory Bricks Market Size and Growth Opportunities and Forecast till 2026 - 2035
- Chemical Distribution System (CDS) Market Size and Growth Opportunities and Forecast till 2026 - 2035
- Liquid Nitrogen Cryopreservation Market Size and Growth Opportunities and Forecast till 2026 - 2035