Automotive Headlamp Reflector Market Size, Share, Trends & Growth Opportunities Forecast to 2026 - 2035
Automotive Headlamp Reflector Market Size, Share & Trends Report, 2026–2035
LAST UPDATED: OCTOBER 2026
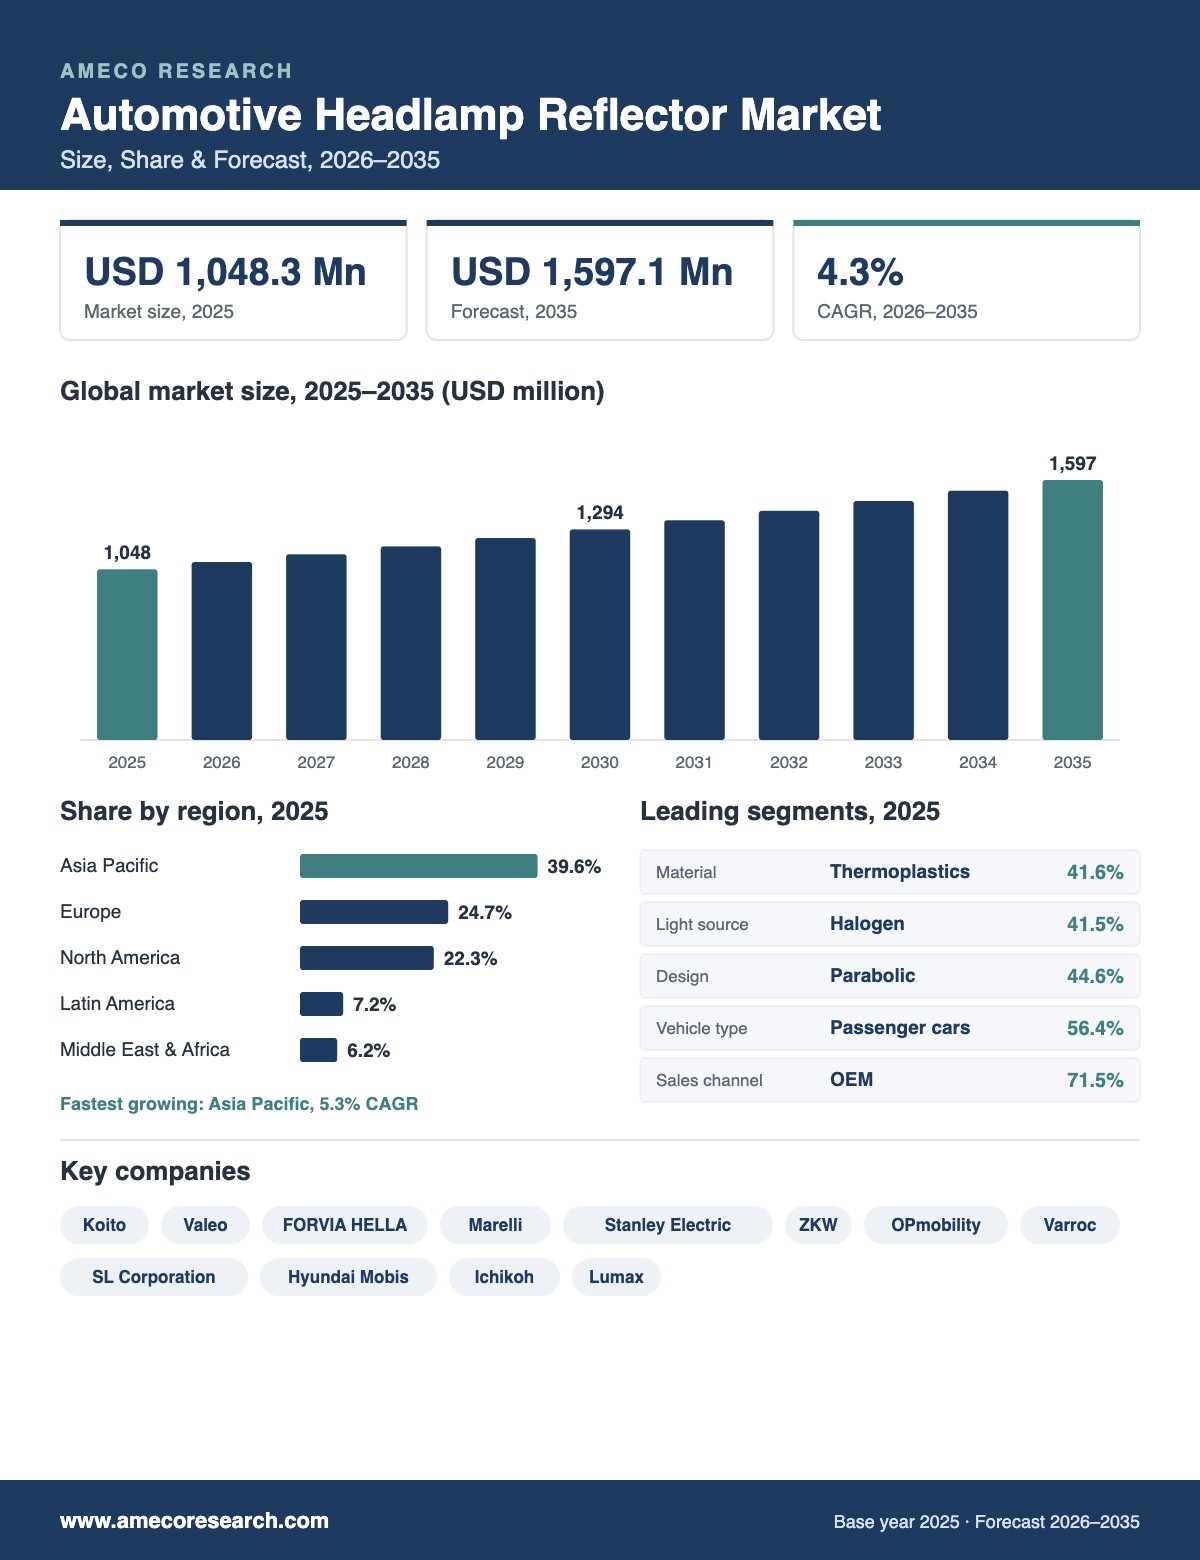
The global automotive headlamp reflector market size was valued at USD 1,048.3 million in 2025 and is projected to reach USD 1,597.1 million by 2035, growing at a CAGR of 4.3% from 2026 to 2035. The market is estimated at USD 1,093.4 million in 2026, with Asia Pacific holding the largest share and registering the fastest growth.
An automotive headlamp reflector is the precision-shaped, mirror-coated component inside a headlamp that gathers light from a halogen bulb, HID lamp or LED and projects it onto the road in a regulated beam pattern. Reflectors are typically injection- or compression-molded from heat-resistant thermoplastics or thermoset composites, then vacuum-metallized with aluminum to achieve reflectivity above 85%.
The reflector decides how far and how evenly a headlamp lights the road, how much glare it causes for oncoming drivers, and whether the lamp passes ECE, SAE and FMVSS 108 beam-pattern tests. As carmakers move from halogen to LED, matrix and adaptive headlamps, reflectors are becoming more complex freeform optics, raising the value of each part even as unit volumes track global vehicle production.
Automotive Headlamp Reflector Market Key Takeaways
Automotive Headlamp Reflector Market Report Scope
| Report Attribute | Details |
| Automotive Headlamp Reflector Market Size in 2025 | USD 1,048.3 Million |
| Automotive Headlamp Reflector Market Size in 2026 | USD 1,093.4 Million |
| Automotive Headlamp Reflector Market Forecast by 2035 | USD 1,597.1 Million |
| Automotive Headlamp Reflector Market CAGR (2026–2035) | 4.3% |
| Historical Data | 2021–2024 |
| Base Year | 2025 |
| Forecast Period | 2026–2035 |
| Largest and Fastest-Growing Region | Asia Pacific (39.6% share in 2025; 5.3% CAGR) |
| Segments Covered | Material, Light Source, Reflector Design, Beam Function, Vehicle Type, Manufacturing Process, Sales Channel and Region |
| Regional Scope | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
| Key Companies Profiled | Koito Manufacturing, Valeo, FORVIA HELLA, Marelli, Stanley Electric, ZKW Group, OPmobility, Varroc Engineering, SL Corporation, Hyundai Mobis, Ichikoh Industries and Lumax Industries |
| Report Coverage | Market size and forecast, trends, drivers, restraints, opportunities, segment and regional analysis, competitive landscape, recent developments |
How Big Is the Automotive Headlamp Reflector Market in 2026?
Ameco Research estimates the automotive headlamp reflector market at USD 1,093.4 million in 2026, up 4.3% from USD 1,048.3 million in 2025. The market is expected to reach about USD 1,293.9 million by 2030 and USD 1,597.1 million by 2035, as LED and adaptive headlamps spread from premium models into mass-market cars, SUVs and commercial vehicles.
| Year | Automotive Headlamp Reflector Market Size (USD Million) |
| 2025 | 1,048.3 |
| 2026 | 1,093.4 |
| 2028 | 1,189.4 |
| 2030 | 1,293.9 |
| 2032 | 1,407.6 |
| 2035 | 1,597.1 |
Latest Automotive Headlamp Reflector Market Trends 2026
LED replaces halogen in mainstream cars
LED headlamps are now standard on most new models in Europe, China and North America and are moving quickly into compact cars and two-row SUVs in India and Southeast Asia. LED optics need tighter surface tolerances and more complex reflector geometries, so reflector value per vehicle is rising.
Freeform reflectors gain ground
Computer-designed freeform surfaces divide the reflector into many segments, each aimed at a different part of the beam. They deliver sharper cut-off lines and more even light with fewer parts, and they suit the slim headlamp designs that stylists prefer.
Adaptive and matrix lighting adds complexity
Adaptive driving beam (ADB) and matrix headlamps switch individual LED segments on and off to avoid dazzling other drivers. FORVIA HELLA’s matrix headlamp for the Zeekr 8X, announced in 2026, uses about 25,000 LED pixels and a 16-zone adaptive module per headlamp, showing how fast lighting content is increasing.
India becomes a lighting manufacturing hub
Lighting suppliers are expanding in India to serve rising domestic vehicle output and exports. In 2026, Valeo outlined plans to invest more than EUR 200 million in India and Marelli-Motherson opened an exterior lighting plant in Sanand, Gujarat, while Koito’s Gujarat plant is designed for about 500,000 headlamps a year.
Lightweight, high-heat polymers
Carmakers want lighter headlamps for EV range and lower emissions. Suppliers are replacing metal and glass with high-temperature thermoplastics and BMC composites that can be molded directly into complex shapes and metallized without a base coat.
EVs and software-defined lighting
Electric and software-defined vehicles use headlamps for brand signatures, welcome animations and road projections. This raises demand for multi-function reflector modules that combine low beam, high beam and signature lighting in one compact unit.
Automotive Headlamp Reflector Market Dynamics
Growth drivers
- Rising vehicle production: every new car, truck and bus needs two or more headlamp reflectors, so demand follows global vehicle output, which is growing fastest in Asia.
- Shift to LED, matrix and adaptive lighting: advanced light sources need precisely engineered reflectors, increasing the value of each unit.
- Road safety regulations: UN ECE, SAE and FMVSS 108 beam-pattern and glare rules require accurate optics, and newer rules allow adaptive driving beams in more markets, including the U.S.
- Vehicle styling and premiumization: slim, signature headlamps are a key design feature, encouraging carmakers to invest in freeform reflector designs.
- Aftermarket replacement demand: collisions, ageing vehicles and headlamp upgrades support steady replacement sales, particularly in large markets such as India, where the automotive aftermarket was valued at nearly INR 1 lakh crore in FY2025.
Restraints and challenges
- Cost of advanced lighting systems: LEDs, sensors, ECUs, thermal management and calibration raise headlamp costs and can slow adoption in entry-level vehicles.
- Projector and lens-based designs: some LED projector and micro-lens array headlamps use fewer or smaller reflectors, limiting reflector content in certain models.
- Raw material price volatility: prices of engineering plastics, resins and aluminum coating materials affect supplier margins.
- Strict quality requirements: reflectors must keep their shape and coating at high temperatures, and any defect can cause beam failures and recalls.
- Vehicle production cycles: slowdowns in car sales, tariffs and supply chain disruptions directly reduce reflector demand.
Opportunities
- Electric vehicles need efficient, lightweight lighting to protect driving range, favoring advanced polymer reflectors.
- Adaptive driving beam adoption in North America and emerging markets opens a new wave of headlamp redesigns.
- Localized manufacturing in India, Mexico, Eastern Europe and Southeast Asia lets suppliers win new OEM programs close to vehicle plants.
- Commercial vehicle upgrades from halogen to LED in trucks and buses create a growing reflector replacement market.
- Direct-metallization materials that remove base-coat steps can lower production costs and improve reflector quality.
Automotive Headlamp Reflector Market Segment Analysis
By material: Why do thermoplastics lead the headlamp reflector market?
Thermoplastics such as polycarbonate, PEI and PBT accounted for 41.6% of revenue in 2025 because they are light, easy to injection-mold into complex shapes and can be metallized directly. Composites, mainly bulk molding compound (BMC), held 37.5% thanks to their excellent heat resistance and dimensional stability near hot light sources.
| Material | Share (2025) | Key Highlights |
| Thermoplastics | 41.6% | PC, PEI and PBT; light, moldable and suitable for direct metallization |
| Composites (BMC/Thermosets) | 37.5% | High heat resistance and shape stability for halogen and HID lamps |
| Aluminum, Sheet Steel & Others | 20.9% | Metal and glass reflectors in legacy, heavy-duty and specialty lamps |
By light source: Is LED overtaking halogen?
Halogen headlamps still accounted for 41.5% of reflector revenue in 2025 because of their large installed base in entry-level cars, commercial vehicles and the aftermarket. LED systems held 36.6% and are the fastest-growing light source, expected to account for well over half of the market by 2035.
| Light Source | Share (2025) | Key Highlights |
| Halogen | 41.5% | Low cost; dominant in entry vehicles, commercial vehicles and aftermarket |
| LED | 36.6% | Fastest-growing; standard in most new models; enables matrix and adaptive beams |
| Xenon / HID | 18.4% | High output; gradually being replaced by LED |
| Laser & Others | 3.5% | Long-range high beams in premium vehicles |
By reflector design
Parabolic reflectors held the largest share at 44.6% in 2025 due to their simple design and low cost. Freeform reflectors, at 27.5%, are the fastest-growing design because they deliver precise, glare-free beam patterns with LED light sources.
| Reflector Design | Share (2025) | Key Highlights |
| Parabolic | 44.6% | Simple, low-cost design used across halogen headlamps |
| Freeform | 27.5% | Fastest-growing; computer-optimized surfaces for LED optics |
| Ellipsoidal (Projector) | 17.8% | Used in projector headlamps with a lens and shield |
| Multifaceted / Segmented | 10.1% | Multiple facets for wide, even light distribution |
By beam function
Low-beam reflectors accounted for 41.4% of revenue in 2025, as the dipped beam is used most and must meet strict glare rules. Combined low-and-high-beam modules held 25.6% and are the fastest-growing function at a 6.3% CAGR, as carmakers integrate both beams in compact LED units.
| Beam Function | Share (2025) | Key Highlights |
| Low Beam | 41.4% | Most-used beam; strict cut-off and glare requirements |
| Low + High Beam (Bi-function) | 25.6% | Fastest-growing at 6.3% CAGR; compact LED modules |
| High Beam | 22.8% | Long-range lighting, increasingly adaptive |
| Fog & Cornering | 10.2% | Wide, short-range beams for bad weather and turns |
By vehicle type: Which vehicles use the most headlamp reflectors?
Passenger cars accounted for 56.4% of demand in 2025, supported by high production volumes and frequent model refreshes. Light commercial vehicles held 25.3%, and medium and heavy commercial vehicles 18.3%, where durable reflectors are needed for long operating hours.
| Vehicle Type | Share (2025) | Key Highlights |
| Passenger Cars | 56.4% | Largest segment; rapid LED adoption and styling-driven redesigns |
| Light Commercial Vehicles | 25.3% | Vans and pickups; growth from e-commerce delivery fleets |
| Medium & Heavy Commercial Vehicles | 18.3% | Trucks and buses; durability and long service life |
By manufacturing process
Injection molding produced 67.4% of reflectors by value in 2025 because it supports high volumes, tight tolerances and complex freeform shapes. Compression molding, used mainly for BMC composites, held 24.3%, with stamping, machining and specialty molding making up the rest.
| Manufacturing Process | Share (2025) | Key Highlights |
| Injection Molding | 67.4% | High-volume, precise production of thermoplastic reflectors |
| Compression Molding | 24.3% | Used for heat-resistant BMC thermoset reflectors |
| Other Processes | 8.3% | Stamping, machining and specialty molding |
By sales channel
OEM sales accounted for 71.5% of revenue in 2025, as reflectors are supplied to carmakers as part of complete headlamp assemblies. The aftermarket held 28.5%, driven by collision repairs, replacements in older vehicles and lighting upgrades.
| Sales Channel | Share (2025) | Key Highlights |
| OEM | 71.5% | Supplied within headlamp assemblies for new vehicles |
| Aftermarket | 28.5% | Collision repair, replacement and lighting upgrades |
Automotive Headlamp Reflector Market Regional Analysis
| Region | Share (2025) | Outlook |
| Asia Pacific | 39.6% | Largest and fastest-growing at a 5.3% CAGR; China, India, Japan, South Korea |
| Europe | 24.7% | Premium LED and matrix lighting; Germany, France, Italy, Czech Republic |
| North America | 22.3% | Adaptive driving beam approval and pickup/SUV demand in the U.S. |
| Latin America | 7.2% | Growing at a 4.3% CAGR; Brazil and Mexico production hubs |
| Middle East & Africa | 6.2% | Aftermarket demand and new assembly plants |
Why does Asia Pacific dominate the automotive headlamp reflector market?
Asia Pacific accounted for about 39.6% of global revenue in 2025 and is forecast to grow at a 5.3% CAGR through 2035. China is the world’s largest vehicle producer, Japan and South Korea are home to Koito, Stanley Electric, Ichikoh, SL Corporation and Hyundai Mobis, and India is attracting new lighting plants from Valeo, Marelli-Motherson and Koito as domestic car production and exports grow.
How are Europe and North America developing?
Europe held about 24.7% of the market in 2025. It leads in premium LED, matrix and pixel headlamps, with major suppliers such as FORVIA HELLA, Valeo, ZKW and OPmobility, and strict UN ECE lighting rules. North America represented about 22.3%, supported by high demand for pickups and SUVs and the U.S. approval of adaptive driving beam headlamps, which is prompting new headlamp programs for upcoming model years.
What about Latin America and the Middle East & Africa?
Latin America accounted for about 7.2% of revenue in 2025 and is expected to grow at a 4.3% CAGR, led by vehicle production in Brazil and Mexico. The Middle East & Africa held about 6.2%, with demand coming mainly from the aftermarket and new vehicle assembly plants in Morocco, South Africa, Egypt and Saudi Arabia.
Automotive Headlamp Reflector Market Segmentation
Automotive Headlamp Reflector Market Leading Companies
The automotive headlamp reflector market is concentrated among global lighting suppliers that design and build complete headlamp systems for carmakers, along with regional specialists and aftermarket producers. Competition centers on optical design, LED and adaptive lighting know-how, material and metallization quality, cost, and the ability to manufacture close to vehicle assembly plants.
Koito Manufacturing · Valeo · FORVIA HELLA · Marelli · Stanley Electric · ZKW Group · OPmobility · Varroc Engineering · SL Corporation · Hyundai Mobis · Ichikoh Industries · Lumax Industries
Recent developments
- May 2026: FORVIA HELLA launched its locally produced SSL|HD high-definition headlamp system in China, debuting on the Zeekr 8X.
- March 2026: FORVIA HELLA announced Galaxy Diamond Matrix headlamps for the Zeekr 8X, with around 25,000 LED pixels and a 16-zone adaptive module in each headlamp.
- February 2026: Valeo outlined plans to invest more than EUR 200 million in India, targeting about EUR 700 million in Indian sales by 2028.
- February 2026: Marelli-Motherson opened a new exterior lighting manufacturing facility in Sanand, Gujarat, India.
- 2026: FORVIA HELLA secured several adaptive headlamp programs from North American carmakers, with series production planned for 2028 and 2029.
Automotive Headlamp Reflector Market: Frequently Asked Questions
How big is the automotive headlamp reflector market?
The global automotive headlamp reflector market was valued at USD 1,048.3 million in 2025 and is estimated at USD 1,093.4 million in 2026. Ameco Research projects it to reach USD 1,597.1 million by 2035, growing at a CAGR of 4.3% from 2026 to 2035.
What is the growth rate of the automotive headlamp reflector market?
The market is expected to grow at a CAGR of 4.3% between 2026 and 2035, supported by rising vehicle production, the shift to LED and adaptive headlamps, and stricter lighting safety regulations.
What is a headlamp reflector?
A headlamp reflector is the curved, mirror-coated surface inside a vehicle headlamp that collects light from the bulb or LED and directs it onto the road in a controlled beam pattern. Reflectors are usually molded from thermoplastics or thermoset composites and given a vacuum-metallized aluminum coating for high reflectivity.
What are the main types of headlamp reflectors?
The main types are parabolic reflectors, freeform (complex-surface) reflectors, ellipsoidal reflectors used in projector headlamps, and multifaceted or segmented reflectors. Parabolic designs held the largest share at about 44.6% in 2025, while freeform reflectors are growing fastest because they pair well with LED light sources.
What material is used for headlamp reflectors?
Most headlamp reflectors are made from thermoplastics such as polycarbonate, PEI and PBT, or from bulk molding compound (BMC) thermoset composites that withstand high heat. Thermoplastics held about 41.6% of revenue in 2025 and composites about 37.5%, with aluminum, sheet steel and glass making up the rest.
How do LED headlamps affect the reflector market?
LED headlamps need precisely shaped reflector surfaces to control light from small, high-intensity chips, which raises the value of each reflector. LED-based systems held about 36.6% of the market in 2025 and are expected to account for well over half of revenue by 2035, overtaking halogen.
Which region leads the automotive headlamp reflector market?
Asia Pacific leads with about 39.6% of global revenue in 2025 and is the fastest-growing region at a 5.3% CAGR, driven by vehicle production in China, India, Japan and South Korea. Europe and North America follow.
Who are the key players in the automotive headlamp reflector market?
Leading companies include Koito Manufacturing, Valeo, FORVIA HELLA, Marelli, Stanley Electric, ZKW Group, OPmobility, Varroc Engineering, SL Corporation, Hyundai Mobis, Ichikoh Industries and Lumax Industries.
Related Automobile & Transportation Market Reports
- Hydrogen Buses Market Size, Share, Trends & Growth Opportunities Forecast to 2026 - 2035
- Electric Vehicle Charging Station Market Growth Opportunities and Forecast till 2035
- Electric Vehicle Market Growth Opportunities and Forecast till 2035
- Car Rental Market Size and Growth Opportunities and Forecast till 2026 - 2035
- Automotive Laser Headlight Market Growth Opportunities and Forecast till 2033