Press Release
Hydrogen Buses Market to Reach USD 64.35 Billion by 2035, Growing at a 38.6% CAGR as Transit Fleets Scale Up
Date : Nov 04, 2026
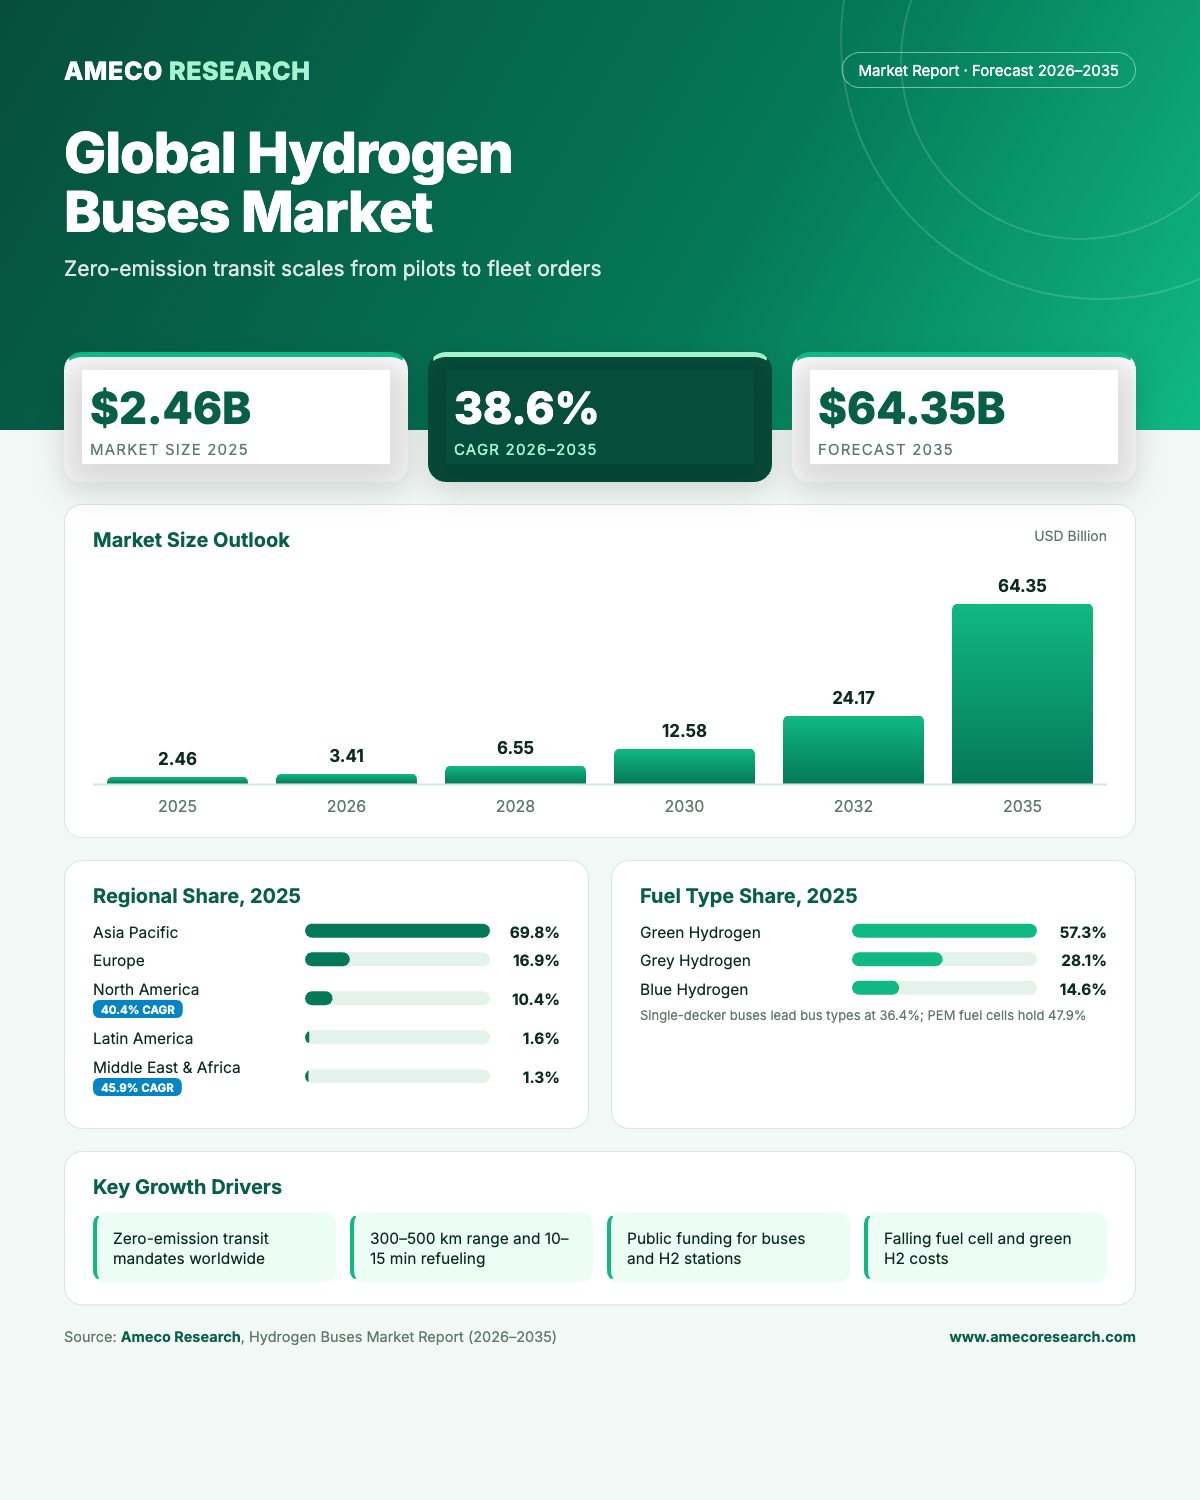
Pune, India, November 4, 2026 — The global Hydrogen Buses Market was valued at USD 2.46 billion in 2025 and is projected to reach USD 64.35 billion by 2035, expanding at a CAGR of 38.6% from 2026 to 2035, according to the latest Hydrogen Buses Market report by Ameco Research. The market is estimated at USD 3.41 billion in 2026. Transit agencies are moving from small pilot fleets to large orders, fuel cell costs are falling, and green hydrogen supply is expanding, which together make hydrogen one of the fastest-growing segments of zero-emission public transport.
Hydrogen buses fill a gap that battery electric buses struggle with: long daily mileage, 18–20 hour shifts, hilly or cold routes, and depots without the grid capacity for large-scale charging. With 300–500 km of range per fill and refueling in 10–15 minutes, they can replace diesel buses one-for-one. The 180-page study covers market size, bus types, fuel and fuel cell technologies, applications, regional demand, and the companies leading the shift.
Hydrogen Buses Market Size and Forecast
Hydrogen buses are zero-emission passenger buses powered by hydrogen, usually through a fuel cell that generates electricity for an electric drivetrain, and less commonly through a hydrogen internal combustion engine. They serve city transit, intercity and coach routes, airport shuttles, tourism, and school transport, and are sold as new vehicles or created by retrofitting diesel buses.
Ameco Research expects the market to pass USD 12.5 billion by 2030 and grow more than twenty-fold over the decade:
| Year | Market Size (USD Billion) |
|---|---|
| 2025 (Base Year) | 2.46 |
| 2026 | 3.41 |
| 2028 | 6.55 |
| 2030 | 12.58 |
| 2032 | 24.17 |
| 2035 | 64.35 |
Key Findings at a Glance
- Market size 2025: USD 2.46 billion, rising to USD 64.35 billion by 2035
- Growth rate: 38.6% CAGR from 2026 to 2035
- Largest region: Asia Pacific, with about 69.8% of 2025 revenue
- Fastest-growing region: Middle East & Africa, at a 45.9% CAGR from a small base
- Largest bus type: Single-decker buses, with 36.4% share
- Leading fuel type: Green hydrogen, with 57.3% of revenue
- Largest application: Public transportation, with 43.1% share
Why Are Transit Agencies Choosing Hydrogen Buses?
Zero-Emission Transit Mandates
Clean vehicle rules in the EU, China, South Korea, Japan, India, and U.S. states such as California require transit agencies to phase out diesel buses. Hydrogen gives operators a zero-emission option for routes where battery buses cannot easily cover the daily distance.
Range, Refueling Speed, and Depot Constraints
Charging hundreds of battery buses overnight can require expensive grid upgrades, while a single hydrogen station can serve a large fleet. Fast refueling also keeps buses in service longer, which matters for high-frequency city and intercity routes.
Public Funding and Falling Fuel Cell Costs
Programs such as the U.S. Regional Clean Hydrogen Hubs, EU Clean Hydrogen Partnership projects, German bus funding schemes, and Chinese purchase subsidies lower the cost of buses and stations. At the same time, higher production volumes, longer stack life, and components shared with trucks keep pushing fuel cell system prices down.
Hydrogen Buses Market Trends in 2026
- From pilots to fleets: Bologna began running Solaris hydrogen buses in 2026 as part of a planned 127-bus fleet, Ruhrbahn in Germany is adding 52 hydrogen buses with public funding, and Porto is deploying 18-meter articulated fuel cell buses on a bus rapid transit corridor.
- Fuel cell supply scales up: Ballard Power Systems secured an order from New Flyer for 500 heavy-duty fuel cell modules totaling about 50 MW, one of the largest bus fuel cell orders to date.
- India enters the market: Cochin International Airport introduced India's first hydrogen-fueled passenger buses, powered by green hydrogen produced on site, and Tata Motors announced hydrogen bus production in Lucknow.
- Green hydrogen gets cheaper: The cost gap between green and grey hydrogen has narrowed from 3–4 times in 2020 to roughly 1.5–2 times in some regions.
- Cheaper entry routes: Retrofitting existing buses can cut costs by around 40–50% versus new vehicles, and hydrogen combustion engine buses need roughly 20–30% lower upfront investment than fuel cell buses.
- Fuel price decides the business case: Hydrogen price at the pump is now the main factor in total cost of ownership, so new projects increasingly secure long-term supply contracts and shared refueling hubs before ordering buses.
Challenges to Wider Adoption
Hydrogen buses remain close to twice as expensive as diesel buses because of fuel cell stacks, carbon-fiber tanks, and low production volumes. Refueling stations are costly to build and maintain, and many cities still have few or none. Delivered hydrogen often costs more per kilometer than diesel or grid electricity, and some early European adopters have scaled back fleets when fuel costs rose. Rapidly improving battery electric buses, along with limited spare parts and technician training, add further pressure.
Hydrogen Buses Market Segmentation
By Bus Type
| Bus Type | Share (2025) | Key Highlights |
|---|---|---|
| Single-Decker | 36.4% | Standard 12 m and articulated city buses; the largest volume segment |
| Fuel Cell Hybrid | 26.6% | Fuel cell plus large battery; 15–25% lower hydrogen consumption |
| Battery-Electric Hydrogen (Range-Extended) | 21.9% | Battery buses with a fuel cell range extender for longer routes |
| Double-Decker | 15.1% | High-capacity urban routes in the U.K., Germany, and Hong Kong |
By Fuel Type and Fuel Cell Technology
Green hydrogen from renewable-powered electrolysis supplied 57.3% of revenue in 2025, because most funding schemes require low-carbon fuel and many agencies install on-site electrolyzers. Grey hydrogen held 28.1% and blue hydrogen 14.6%. Proton exchange membrane fuel cells (PEMFC) lead fuel cell technology with 47.9%, thanks to fast start-up and high power density, followed by alkaline (29.2%) and solid oxide fuel cells (19.6%).
By Manufacturing, Power Output, and Application
New-build buses accounted for 71.6% of revenue and retrofits for 28.4%. Systems rated 100–200 kW, which match standard city buses, held the largest power output share at 44.6%. Public transportation led applications with 43.1%, followed by tourism and airport transportation (27.4%), private transportation (19.2%), and school transportation (10.3%).
Regional Outlook
| Region | Share (2025) | Outlook |
|---|---|---|
| Asia Pacific | 69.8% | Largest market; China, South Korea, and Japan lead, with India emerging |
| Europe | 16.9% | Germany, the U.K., Italy, France, Poland, and the Netherlands |
| North America | 10.4% | Growing at a 40.4% CAGR, led by California transit agencies |
| Latin America | 1.6% | Early projects in Brazil, Chile, and Colombia |
| Middle East & Africa | 1.3% | Fastest-growing at a 45.9% CAGR; Gulf hydrogen strategies |
China operates the world's largest hydrogen bus fleet through its fuel cell vehicle demonstration city clusters, and South Korea has rolled out thousands of fuel cell buses with strong subsidies. In Europe, more than 1,500 hydrogen buses were on order by 2024, supported by EU clean vehicle rules. In the Middle East, Saudi Arabia, the UAE, Oman, and Egypt are linking large green hydrogen projects to public transport.
Leading Companies in the Hydrogen Buses Market
The market brings together bus manufacturers, fuel cell suppliers, and automakers. Chinese and Korean OEMs dominate volumes in Asia, while European builders such as Wrightbus, Solaris, and CaetanoBus lead in Europe. Competition centers on fuel cell durability, hydrogen consumption, total cost of ownership, and the ability to deliver buses together with refueling and service packages. Companies profiled include Toyota Motor Corporation, Hyundai Motor Company, Ballard Power Systems, Wrightbus, Solaris Bus & Coach, CaetanoBus, Daimler Truck AG, Volvo Group, NFI Group (New Flyer), Tata Motors, Ashok Leyland, Yutong Bus, and Beiqi Foton Motor.
Want to discuss company profiles, pricing, or methodology? Make an Inquiry with an Ameco Research analyst.
Where Are the Biggest Opportunities?
- Low-cost green hydrogen: Large electrolyzer projects are expected to bring fuel costs closer to diesel over the next decade.
- Shared hydrogen hubs: Stations that serve buses, trucks, and industry from one site improve utilization and cut fuel cost per kilogram.
- Airport, tourism, and intercity coaches: Long, predictable routes suit hydrogen well and are opening new demand.
- Retrofit programs: Converting diesel buses offers a cheaper, faster way to decarbonize fleets.
- Emerging markets: India, the Middle East, and Latin America are launching national hydrogen strategies that include public transport.
Readers following the clean mobility and hydrogen value chain may also find these Ameco Research studies useful: the Electric Bus Market report, the Hydrogen Generation Market analysis, the Hydrogen Energy Storage Market report, and the Electric Vehicle Market forecast.
Report Scope
| Report Attribute | Details |
|---|---|
| Market Size in 2025 | USD 2.46 Billion |
| Market Forecast in 2035 | USD 64.35 Billion |
| CAGR (2026–2035) | 38.6% |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2035 |
| Segments Covered | Bus Type, Fuel Type, Propulsion Type, Manufacturing, Power Output, Fuel Cell Technology, Application, Region |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Report Coverage | Market size and forecast, trends, drivers, restraints, opportunities, segment and regional analysis, competitive landscape, recent developments |
| Pages | 180 |
Who Will Benefit From This Report?
- Transit agencies and bus operators comparing hydrogen, battery electric, and retrofit options for fleet replacement.
- Bus OEMs and fuel cell suppliers sizing demand by bus type, power output, and region.
- Hydrogen producers and refueling station developers planning supply for transit hubs.
- Investors and infrastructure funds evaluating fuel cell, hydrogen, and clean mobility opportunities.
- Policymakers, consultants, and energy companies designing zero-emission transport programs.
The report supports investment planning with ten-year forecasts, business strategy with segment growth rates, market entry with regional and country analysis, and competitive intelligence with company profiles and recent orders. Buy the Hydrogen Buses Market Report for immediate access.
Conclusion
The Hydrogen Buses Market is moving from demonstration projects to commercial fleets. With revenue forecast to climb from USD 2.46 billion in 2025 to USD 64.35 billion by 2035 at a 38.6% CAGR, the winners will be the companies and cities that secure affordable green hydrogen, build shared refueling infrastructure, and keep fuel cell costs falling. Ameco Research's report gives decision-makers the data to plan that transition with confidence.
Explore the Hydrogen Buses Market Report
Preview the data and methodology, ask about pricing and coverage, get the complete 180-page study, or request extra segments, country-level data, and research beyond the report’s scope.
About Ameco Research
Ameco Research is a market research and consulting firm that provides syndicated reports, customized research, and data-driven insight across industries including automotive and transportation, energy, ICT, healthcare, and chemicals. Its analysts help businesses, investors, and institutions find growth opportunities and make informed strategic decisions.
Contact Us
Ameco Research
201, Vaidehi-Saaket, Baner - Pashan Link Rd, Pashan, Pune, Maharashtra 411021, India
Phone: +91 898 322 5533
E-mail: [email protected]
Website: www.amecoresearch.com