Press Release
Semiconductor Memory Market Triples to USD 784.5 Billion in 2026, Set to Reach USD 1,418.2 Billion by 2035 | Ameco Research
Date : Nov 13, 2026
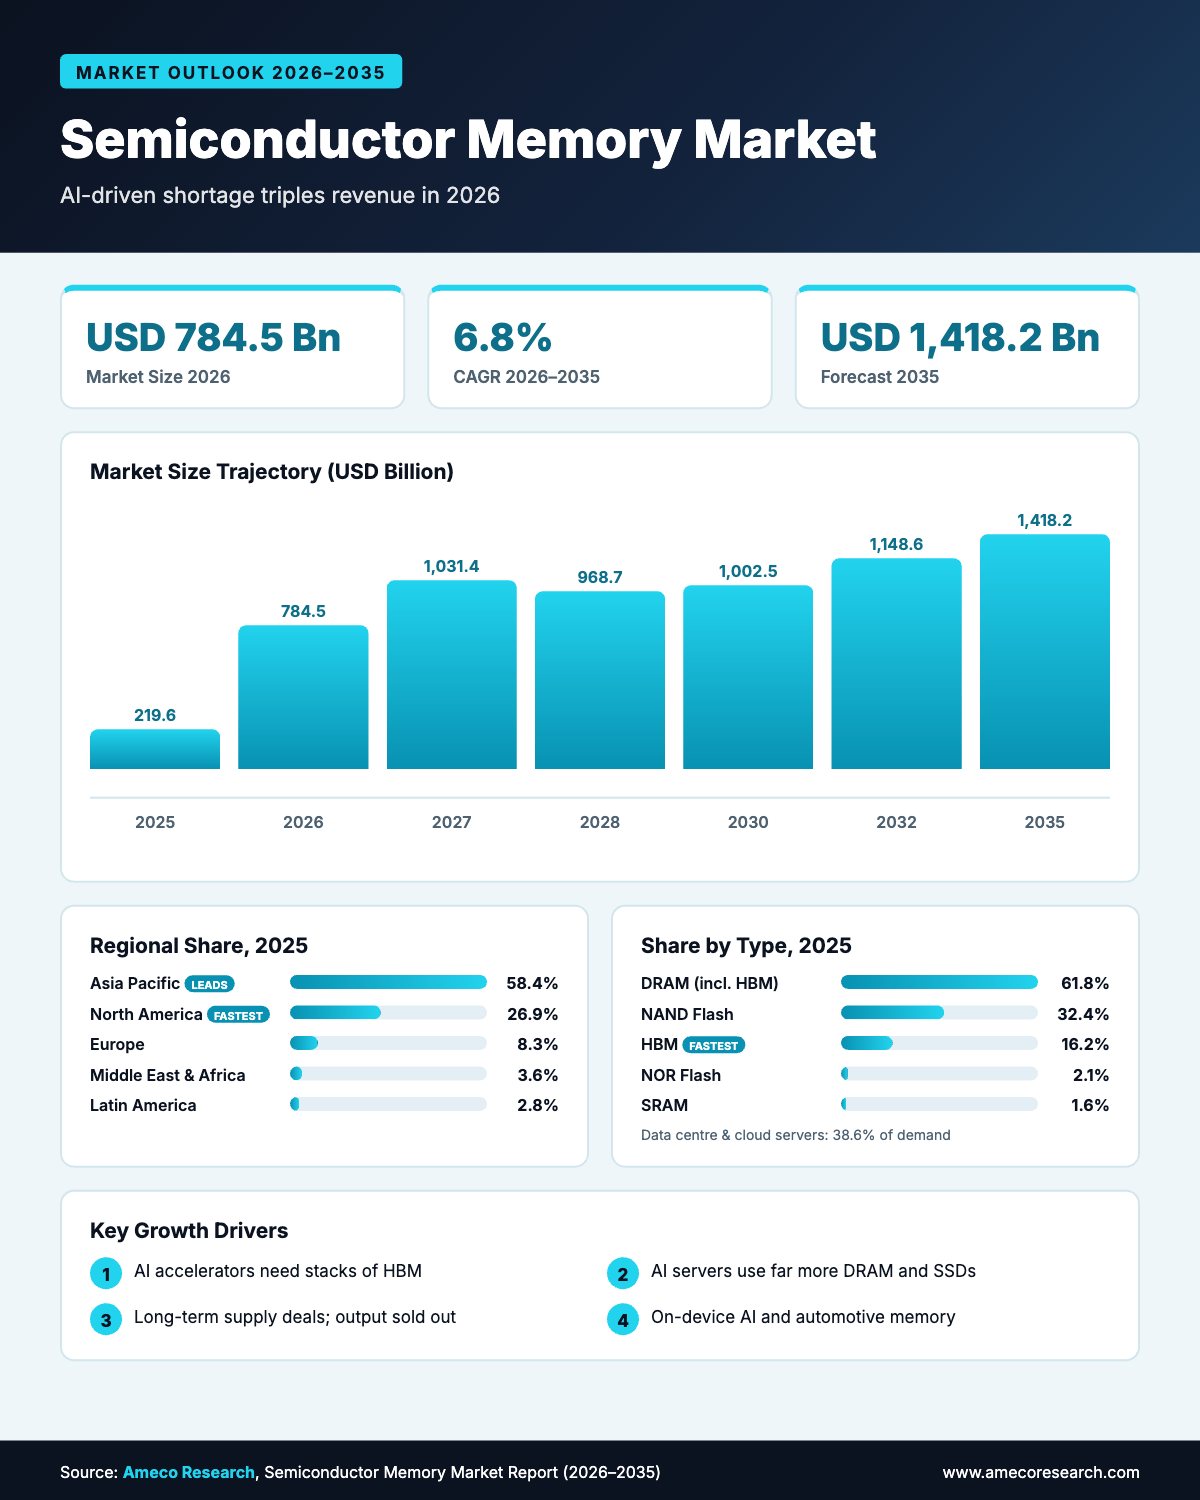
Pune, India, November 13, 2026 — The global semiconductor memory market more than tripled in a single year, from USD 219.6 billion in 2025 to an estimated USD 784.5 billion in 2026, and is projected to reach USD 1,418.2 billion by 2035, growing at a CAGR of 6.8% from 2026 to 2035, according to the new Semiconductor Memory Market report from Ameco Research. An AI-driven shortage of DRAM, high-bandwidth memory (HBM), and NAND flash has turned memory into the largest segment of the global chip industry.
Semiconductor memory refers to the integrated circuits that store data in electronic devices. The market covers volatile memory, mainly DRAM and HBM, which holds data while a device is running, and non-volatile memory, mainly NAND and NOR flash, which keeps data when power is off. It also includes SRAM, EEPROM, and emerging memories such as MRAM, ReRAM, and phase-change memory. Every AI accelerator needs stacks of HBM, and AI servers use several times more DRAM and SSD storage than conventional servers. As AI data-centre spending surged, demand outran supply and memory prices climbed every quarter in 2026.
How Big Is the Semiconductor Memory Market?
Ameco Research estimates the market at USD 784.5 billion in 2026, more than three times its 2025 level, as AI servers absorbed HBM, DDR5, and enterprise SSD supply. Revenue is expected to rise further to about USD 1,031.4 billion in 2027, ease in 2028 and 2029 as new fabs add capacity and prices normalise, and then grow steadily to USD 1,418.2 billion by 2035. This shape reflects memory’s classic boom-and-correction cycle, but at a permanently higher level of demand set by AI infrastructure.
| Year | Market Size (USD Billion) |
|---|---|
| 2025 | 219.6 |
| 2026 | 784.5 |
| 2027 | 1,031.4 |
| 2028 | 968.7 |
| 2029 | 941.3 |
| 2030 | 1,002.5 |
| 2032 | 1,148.6 |
| 2035 | 1,418.2 |
Key Takeaways
- Market size: USD 219.6 billion in 2025, about USD 784.5 billion in 2026, and USD 1,418.2 billion by 2035.
- Growth rate: 6.8% CAGR from 2026 to 2035, from a much higher post-shortage base.
- Leading region: Asia Pacific, with about 58.4% of 2025 revenue.
- Fastest-growing region: North America, at a 7.9% CAGR.
- Leading type: DRAM including HBM, at 61.8% of revenue; NAND flash held 32.4%.
- Fastest-growing product: HBM, at about 16.2% of 2025 memory revenue.
- Leading application: Data centre and cloud servers, at 38.6% and growing fastest.
What Is Driving the Semiconductor Memory Market?
The AI memory supercycle
AI data centres have created the biggest memory shortage in more than a decade. Industry trade statistics published in spring 2026 projected memory revenue to grow by about 250% in 2026 to more than USD 800 billion, making memory over half of global semiconductor sales. SK hynix reported third-quarter 2026 revenue of KRW 104.6 trillion with a record 80% operating margin.
Long-term agreements replace spot buying
Customers are signing multi-year contracts to secure supply. By the third quarter of 2026, SK hynix had long-term agreements with 14 major customers covering more than half of its planned 2027 and 2028 capacity, and said its DRAM and HBM output is effectively sold out through 2029. This shift gives memory makers unusual revenue visibility in a historically volatile business.
On-device AI and automotive electronics
AI smartphones and PCs need more and faster DRAM, such as LPDDR5X, and larger storage. Advanced driver assistance, autonomous driving, and software-defined vehicles are also raising memory content per car, while 5G, IoT, and edge servers add steady demand for DRAM, NAND, and NOR flash.
Enterprise SSDs and high-layer NAND
AI inference and large data lakes are driving demand for high-capacity enterprise SSDs. Manufacturers are moving to 300-plus-layer NAND, such as SK hynix’s 321-layer TLC, and to quad-level cell (QLC) drives that pack more data into each chip.
Key Market Trends
- Price surge across devices: DRAM average selling prices rose by high-20s percent quarter over quarter in the third quarter of 2026, and NAND prices by mid-20s percent, raising prices of smartphones, PCs, and consoles.
- HBM4 ramp: SK hynix expects HBM4 to overtake HBM3E in shipments and revenue in the fourth quarter of 2026, while Samsung and Micron ramp HBM4 for NVIDIA, AMD, and custom AI chips.
- New fabs and supply diversification: Kioxia and Sandisk plan to invest more than USD 31 billion in Japan through 2032, Micron is building new U.S. fabs, and Chinese makers CXMT and YMTC continue to expand.
- CXL and memory pooling: Compute Express Link lets servers share and expand memory, improving utilisation in AI and cloud clusters.
- Processing-in-memory: Moving some computation into memory chips reduces data movement and power use in AI workloads.
Challenges
Memory remains one of the most cyclical parts of the chip industry, and the report expects revenue to ease in 2028 and 2029 as new capacity comes online. Leading-edge DRAM and NAND fabs cost tens of billions of dollars, and HBM stacking, advanced packaging, and 300-plus-layer NAND are hard to manufacture at high yields. U.S. export controls on advanced chips and tools affect supply chains and Chinese producers. High memory prices can also cause demand destruction, reducing sales of smartphones, PCs, and other consumer devices and squeezing device makers’ margins.
Segment Analysis
By type: why DRAM leads
DRAM, including HBM, accounted for 61.8% of revenue in 2025, or about USD 135.7 billion. HBM alone made up about 16.2% of total memory revenue and is the fastest-growing product. NAND flash held 32.4%, driven by enterprise SSDs, smartphones, and PCs.
| Type | Share, 2025 | Key Highlights |
|---|---|---|
| DRAM (incl. HBM) | 61.8% | Server DDR5, LPDDR5X, and HBM for AI |
| – of which HBM | 16.2% | Fastest growing; HBM3E and HBM4 |
| NAND flash | 32.4% | Enterprise SSDs, smartphones, PCs |
| NOR flash | 2.1% | Code storage in automotive, industrial, IoT |
| SRAM | 1.6% | High-speed cache and networking |
| Emerging memory | 0.7% | MRAM, ReRAM, PCM for embedded and edge AI |
| Others (ROM, EEPROM) | 1.4% | Configuration and small data storage |
By application: where memory is used most
| Application | Share, 2025 | Key Highlights |
|---|---|---|
| Data centre & cloud servers | 38.6% | Largest and fastest growing |
| Smartphones & mobile devices | 24.1% | LPDDR5X and UFS for AI phones |
| PCs & laptops | 13.8% | DDR5 and client SSDs; AI PC upgrades |
| Consumer electronics | 8.7% | TVs, consoles, wearables |
| Automotive | 6.2% | ADAS, infotainment, autonomous driving |
| Industrial | 4.9% | Automation, medical, IoT |
| Others | 3.7% | Networking, telecom, aerospace |
Regional Outlook
| Region | Share, 2025 | Outlook |
|---|---|---|
| Asia Pacific | 58.4% | Largest; South Korea, China, Taiwan, Japan |
| North America | 26.9% | Fastest growing at 7.9% CAGR |
| Europe | 8.3% | Automotive, industrial, data centres |
| Middle East & Africa | 3.6% | Gulf AI data-centre build-outs |
| Latin America | 2.8% | Consumer electronics and data centres |
Asia Pacific dominates because South Korea’s Samsung Electronics and SK hynix supply most of the world’s DRAM and HBM, Japan’s Kioxia makes NAND with Sandisk, Taiwan is home to Nanya, Winbond, and Macronix, and China’s CXMT and YMTC are scaling quickly. North America is the fastest-growing region: U.S. hyperscalers and AI companies are the largest buyers of HBM and server memory, Micron is building new fabs in Idaho and New York with CHIPS Act support, and SK hynix is building an advanced HBM packaging plant in Indiana.
Competitive Landscape
The market is highly concentrated. Samsung Electronics, SK hynix, and Micron Technology lead DRAM and HBM, while Kioxia, Sandisk, Samsung, SK hynix, and Micron lead NAND. Other companies profiled include CXMT, YMTC, Nanya Technology, Winbond Electronics, Macronix International, Infineon Technologies, Integrated Silicon Solution (ISSI), GigaDevice, and Everspin Technologies. Competition centres on process technology, HBM qualification with AI chipmakers, capacity, yields, and long-term customer agreements. For supplier benchmarking or pricing analysis, make an inquiry with Ameco Research.
Opportunities Ahead
- HBM4 and custom HBM with logic base dies designed for specific AI chips.
- CXL memory expansion and pooling for AI and cloud servers.
- Emerging memories such as MRAM and ReRAM for embedded and edge AI.
- Automotive-grade memory for autonomous and software-defined vehicles.
Explore related coverage in Ameco Research’s High Bandwidth Memory (HBM) Market, Semiconductor Market, AI Data Center Market, and Server Market reports.
Report Scope
| Attribute | Details |
|---|---|
| Market size (2025 / 2026) | USD 219.6 billion / USD 784.5 billion |
| Market size (2035) | USD 1,418.2 billion |
| CAGR (2026–2035) | 6.8% |
| Historical data / base year | 2021–2024 / 2025 |
| Segments covered | Type, application, region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Who Should Read This Report
- Memory manufacturers, foundries, and packaging providers planning capacity.
- Hyperscalers, server OEMs, and device makers managing memory costs and supply.
- Equipment and materials suppliers to DRAM, HBM, and NAND fabs.
- Investors tracking the memory cycle and AI infrastructure.
The full report includes pricing and supply analysis, capacity and fab investment tracking, segment and country forecasts, and company profiles. To access it, buy the report.
Frequently Asked Questions
How big is the semiconductor memory market?
The market was USD 219.6 billion in 2025, is estimated at USD 784.5 billion in 2026, and is projected to reach USD 1,418.2 billion by 2035, according to Ameco Research.
Why did the memory market triple in 2026?
AI data centres absorbed HBM, DDR5, and enterprise SSD supply, creating a shortage that pushed DRAM and NAND prices up sharply every quarter.
Will memory prices keep rising?
The report expects revenue to peak around 2027 and ease in 2028 and 2029 as new capacity comes online, before growing steadily again through 2035.
Which memory type is largest?
DRAM, including HBM, accounted for 61.8% of 2025 revenue, followed by NAND flash at 32.4%.
Who are the leading semiconductor memory companies?
Key players include Samsung Electronics, SK hynix, Micron Technology, Kioxia, Sandisk, CXMT, and YMTC.
Conclusion
AI has permanently reset the size of the semiconductor memory market. After tripling in 2026, the market is forecast to reach USD 1,418.2 billion by 2035. Long-term supply agreements, the HBM4 transition, and new fabs in the U.S., Japan, and China will decide who captures the next phase of growth.
Explore the complete Semiconductor Memory Market report for detailed forecasts and competitive analysis.
About Ameco Research
Ameco Research is a market research and consulting firm that provides syndicated reports, custom research, and strategic advisory services across technology, healthcare, energy, automotive, chemicals, and consumer markets. Its analysts combine primary interviews with secondary research to help clients identify growth opportunities and make confident decisions.
Contact Us
Ameco Research
201, Vaidehi-Saaket, Baner - Pashan Link Rd, Pashan, Pune 411021
Phone: +91 898 322 5533
Email: [email protected]
Website: www.amecoresearch.com