Press Release
AI Data Center Market to Reach USD 212.23 Billion by 2035, Growing at a 28.1% CAGR
Date : Nov 03, 2026
Pune, India, November 3, 2026 — The global AI Data Center Market was valued at USD 17.84 billion in 2025 and is projected to reach USD 212.23 billion by 2035, expanding at a compound annual growth rate (CAGR) of 28.1% from 2026 to 2035, according to the newly published AI Data Center Market report by Ameco Research. The market is estimated at USD 22.85 billion in 2026, and the study finds that generative AI, large language model (LLM) training, and fast-rising inference workloads are pushing data center infrastructure through its biggest redesign in decades.
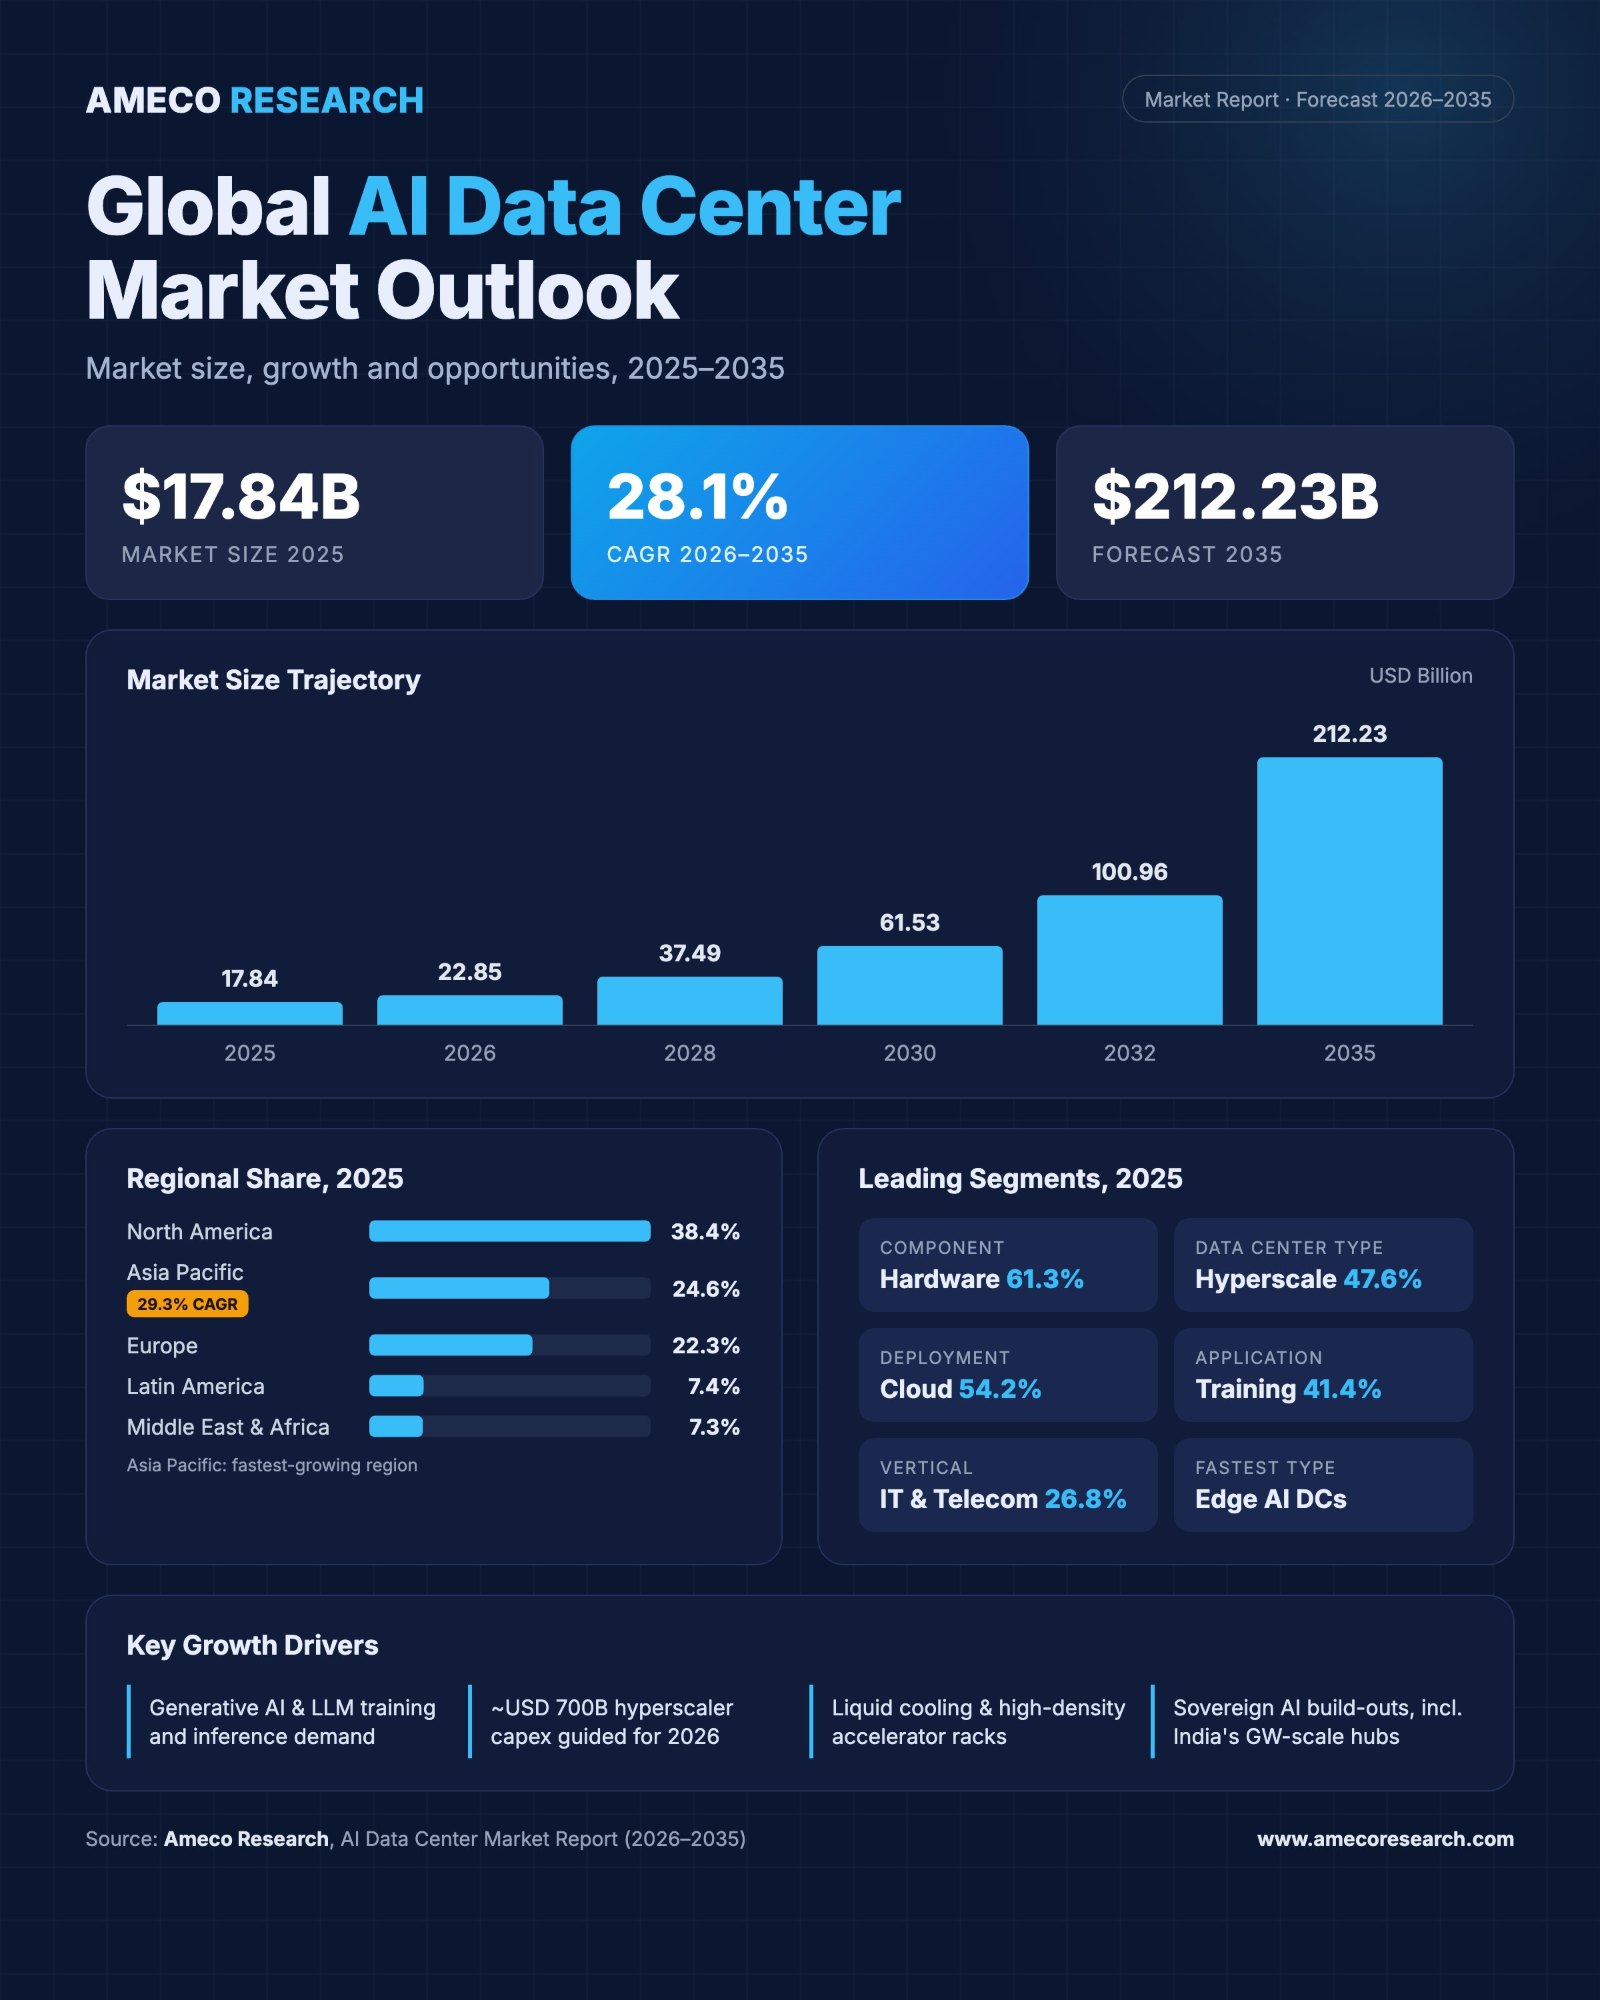
AI Data Center Market Size and Forecast, 2025–2035. Source: Ameco Research.
Hyperscale cloud providers, colocation operators, chipmakers, and enterprises are racing to build facilities designed for GPU- and accelerator-dense computing. The 180-page report covers the market size, segment shares, regional opportunities, construction economics, competitive landscape, and the investment themes that will shape AI infrastructure through 2035.
What Is the Size of the AI Data Center Market?
An AI data center is a facility built or retrofitted to run artificial intelligence workloads, especially model training and inference, on accelerated hardware such as GPUs, custom ASICs, and high-bandwidth networking. Compared with a conventional enterprise data center, it runs far higher rack power densities, depends increasingly on liquid cooling, and needs much larger grid connections.
According to Ameco Research, the AI Data Center Market is on a steep expansion path:
| Year | Market Value (USD Billion) |
|---|---|
| 2025 (Base Year) | 17.84 |
| 2026 | 22.85 |
| 2028 | 37.49 |
| 2030 | 61.53 |
| 2032 | 100.96 |
| 2035 | 212.23 |
At a 28.1% CAGR, the market is set to grow more than ninefold over the forecast period. The report uses 2021–2024 as the historical period, 2025 as the base year, and 2026–2035 as the forecast period.
AI Data Center Market Report Highlights
- Market size 2025: USD 17.84 billion
- Market forecast 2035: USD 212.23 billion
- CAGR (2026–2035): 28.1%
- Largest region: North America, with a 38.4% share in 2025
- Fastest-growing region: Asia Pacific, at a 29.3% CAGR
- Leading component: Hardware, with a 61.3% share (about USD 10.9 billion)
- Leading data center type: Hyperscale, with a 47.6% share
- Leading application: AI model training, with a 41.4% share
Key Growth Drivers of the AI Data Center Market
Generative AI and Large Language Model Adoption
Training and serving frontier and enterprise LLMs requires very large clusters of tightly networked accelerators. As generative AI moves from pilots into production in customer service, software development, content creation, and analytics, demand for purpose-built AI compute capacity keeps climbing.
Record Hyperscaler Capital Expenditure
The report notes that hyperscaler capital expenditure guidance for 2026 is roughly USD 700 billion, up from about USD 410 billion in 2025. Much of that spending goes to AI-ready campuses, accelerators, power infrastructure, and cooling. Ameco Research also highlights Meta raising its 2026 capex guidance to USD 125–145 billion in April 2026.
Accelerator Innovation and Higher Rack Densities
Each new generation of AI accelerators, such as NVIDIA's Vera Rubin platform, which entered full production in January 2026, raises power and thermal requirements per rack. That forces operators to upgrade power distribution, cooling, and networking, and it creates replacement demand across the installed base.
Data Sovereignty and Sovereign AI Programs
Governments increasingly want AI workloads and sensitive data processed within their own borders. These sovereign AI initiatives are opening new capacity demand in Europe, India, the Middle East, and other regions beyond the traditional U.S. hubs.
AI Data Center Market Trends to Watch
- Gigawatt-scale campuses become the benchmark: Sites such as the OpenAI/Oracle Stargate campus in Abilene, Texas (about 1.2 GW) and xAI's Colossus 2 in Memphis, which the report identifies as the largest tracked operating AI data center at about 946 MW as of September 2026, are redefining what "large" means.
- Liquid cooling becomes the default: With rack power expected to approach 600 kW around 2027, direct-to-chip and immersion cooling are moving from niche to standard design.
- 800 VDC power architecture: High-voltage DC power distribution is gaining momentum as a way to cut conversion losses and support extreme rack densities.
- Power availability drives site selection: Grid access now matters as much as land, fiber, or tax incentives when operators choose locations.
- India emerges as a growth center: Google's USD 15 billion, 1 GW AI hub in Visakhapatnam and an USD 11 billion, 1 GW joint venture announced by Reliance, Brookfield, and Digital Realty point to India's rising role in AI infrastructure.
Challenges Facing the AI Data Center Industry
Strong growth comes with real constraints. The report identifies high capital intensity as a key restraint: in 2026, a standard shell-and-core build costs about USD 11.3 million per MW, up from roughly USD 7.7 million per MW in 2020. AI-optimized, liquid-cooled facilities can exceed USD 20 million per MW, and fully loaded sites with IT equipment can cost USD 30–40 million per MW.
Other challenges include limited grid capacity and rising energy costs, sustainability scrutiny, supply-chain and skilled-labor shortages, and uncertain returns on AI investments. Local pushback is also growing. In September 2026, Loudoun County, Virginia, paused new data center applications.
AI Data Center Market Segmentation Analysis
By Component
Hardware leads with a 61.3% share in 2025, driven by spending on accelerators, servers, storage, networking, power, and cooling equipment. Services (20.6%) is the fastest-growing component as operators look for design, integration, and managed-operations expertise. Software accounts for 18.1%.
By Deployment
Cloud-based deployment holds 54.2% of the market, followed by on-premises at 25.6% and hybrid at 20.2%. Hybrid is the fastest-growing model because enterprises want cloud scalability while keeping sensitive AI workloads under their own control.
By Data Center Type
Hyperscale facilities dominate with 47.6%, followed by enterprise (18.3%), colocation (14.4%), edge (11.9%), and modular and portable data centers (7.8%). Edge AI data centers are the fastest-growing type as inference moves closer to users and devices.
By Application
AI model training leads with 41.4%, followed by AI model inference (20.7%), big data analytics (15.3%), computer vision processing (10.2%), natural language processing (7.8%), autonomous systems and robotics (2.9%), and cybersecurity and fraud detection (1.7%). NLP is the fastest-growing application.
By Industry Vertical
IT and telecom is the largest end-use vertical at 26.8%, followed by BFSI (14.2%), healthcare (11.7%), retail and e-commerce (10.3%), and manufacturing (9.1%). Healthcare is the fastest-growing vertical, reflecting demand for medical imaging AI, drug discovery, and clinical decision support.
AI Data Center Market Regional Outlook
| Region | 2025 Share | Key Insight |
|---|---|---|
| North America | 38.4% | Largest market, anchored by U.S. hyperscale and gigawatt campuses |
| Asia Pacific | 24.6% | Fastest-growing region at a 29.3% CAGR, led by China, India, Japan, and South Korea |
| Europe | 22.3% | Shaped by sovereign AI initiatives and the EU AI Act |
| Latin America | 7.4% | Rising investment in Brazil, Mexico, and Chile |
| Middle East & Africa | 7.3% | UAE and Saudi Arabia lead national AI infrastructure programs |
North America remains the center of gravity for AI infrastructure, while Asia Pacific offers the strongest growth runway as India, China, and Southeast Asia add capacity. Country-level analysis covers the U.S., Canada, the U.K., Germany, France, Spain, China, India, Japan, South Korea, Australia, Brazil, Mexico, the GCC, and South Africa.
Competitive Landscape: Leading Companies in the AI Data Center Market
The AI data center ecosystem brings together chip designers, cloud platforms, colocation specialists, server OEMs, networking vendors, and power and cooling suppliers. Companies profiled in the report include:
- Accelerators and semiconductors: NVIDIA, AMD, Intel, Broadcom
- Cloud and hyperscale operators: Microsoft, Amazon Web Services, Google, Meta, Oracle, CoreWeave
- Colocation and data center REITs: Equinix, Digital Realty
- Servers and systems: Dell Technologies, Hewlett Packard Enterprise, Super Micro Computer, IBM
- Networking: Cisco Systems, Arista Networks
- Power and cooling infrastructure: Vertiv, Schneider Electric
The report also tracks major 2026 developments, including Anthropic's 20-year, USD 19 billion lease with TeraWulf in Kentucky, the roughly 910 MW Anthropic–Amazon campus in New Carlisle, Indiana, and Microsoft's Fairwater AI sites in Atlanta and Wisconsin.
Have questions about company profiles, pricing, or methodology? Make an Inquiry and an Ameco Research analyst will respond.
Investment Opportunities and Future Outlook
Ameco Research identifies several high-potential opportunity areas for investors and operators through 2035:
- Energy-efficient and green AI data centers that pair renewable power, heat reuse, and advanced cooling to meet sustainability targets.
- Inference and edge capacity as deployed AI models drive demand for distributed, low-latency infrastructure.
- Emerging markets in India, the Middle East, Latin America, and Southeast Asia, where sovereign AI programs and digital growth are creating new capacity needs.
- Modular and prefabricated builds that shorten deployment timelines and reduce construction risk.
Adjacent infrastructure markets will benefit too. Readers tracking the wider ecosystem can explore Ameco Research's Data Center Cooling Market report, the Data Center Battery Market analysis, the Enterprise AI Market forecast, and the Physical AI Market study.
Report Scope and Coverage
| Report Attribute | Details |
|---|---|
| Market Size in 2025 | USD 17.84 Billion |
| Market Forecast in 2035 | USD 212.23 Billion |
| CAGR (2026–2035) | 28.1% |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2035 |
| Segments Covered | Component, Deployment, Data Center Type, Application, Industry Vertical, Region |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Report Coverage | Market size and forecast, trends, drivers, restraints, opportunities, segment and regional analysis, construction cost benchmarks, competitive landscape, and recent developments |
| Pages | 180 |
Who Should Read This AI Data Center Market Report?
The report is built for decision-makers who need reliable numbers and clear context on AI infrastructure:
- Investors, private equity, and infrastructure funds assessing data center platforms, REITs, and AI hardware exposure.
- Data center operators and colocation providers planning capacity, site selection, and power strategy.
- AI companies and cloud service providers benchmarking compute build-outs and regional expansion.
- Technology, semiconductor, power, and cooling vendors sizing addressable markets and prioritizing segments.
- Consultants, utilities, and policymakers evaluating grid impact, sustainability, and economic development.
How the Report Supports Business Decisions
- Investment planning: Ten-year forecasts and segment growth rates help investors judge where capital will earn the strongest returns.
- Business strategy: Segment and vertical shares show where demand is concentrated and where it is accelerating.
- Market entry: Regional and country-level analysis identifies high-growth geographies and the constraints to plan around.
- Competitive intelligence: Company profiles and recent developments reveal how leaders are positioning for the next phase of AI infrastructure.
Ready to act on the data? Buy the AI Data Center Market Report for immediate access to the full study.
Conclusion
The AI Data Center Market is moving from an emerging niche to the core of global digital infrastructure. With the market forecast to grow from USD 17.84 billion in 2025 to USD 212.23 billion by 2035 at a 28.1% CAGR, the winners will be those who secure power, master high-density cooling, and place capacity where AI demand is heading next. Ameco Research's report gives investors, operators, and technology providers the data and insight to plan with confidence.
Explore the AI Data Center Market Report
Preview the data tables and methodology, ask about pricing, licensing and coverage, get immediate access to the complete 180-page study, or request additional segments, country-level data and research beyond the report’s scope.
About Ameco Research
Ameco Research is a market research and consulting firm that provides syndicated reports, customized research, and data-driven insight across industries including ICT and media, semiconductors and electronics, healthcare, energy, and automotive. Its analysts help businesses, investors, and institutions find growth opportunities and make informed strategic decisions.
Contact Us
Ameco Research
201, Vaidehi-Saaket, Baner - Pashan Link Rd, Pashan, Pune, Maharashtra 411021, India
Phone: +91 898 322 5533
E-mail: [email protected]
Website: www.amecoresearch.com