Press Release
AI in Asset Management Market to Reach USD 32.66 Billion by 2035, Growing at a 21.6% CAGR as AI Agents Enter Investment Workflows
Date : Nov 10, 2026
Pune, India, November 10, 2026 — The global AI in Asset Management Market was valued at USD 4.62 billion in 2025 and is projected to reach USD 32.66 billion by 2035, growing at a CAGR of 21.6% from 2026 to 2035, according to the new AI in Asset Management Market report from Ameco Research. The market is estimated at USD 5.62 billion in 2026. Fee pressure, exploding data volumes, and rising client expectations are pushing investment firms to move AI out of niche quant strategies and into research, portfolio management, risk, operations, and client service.
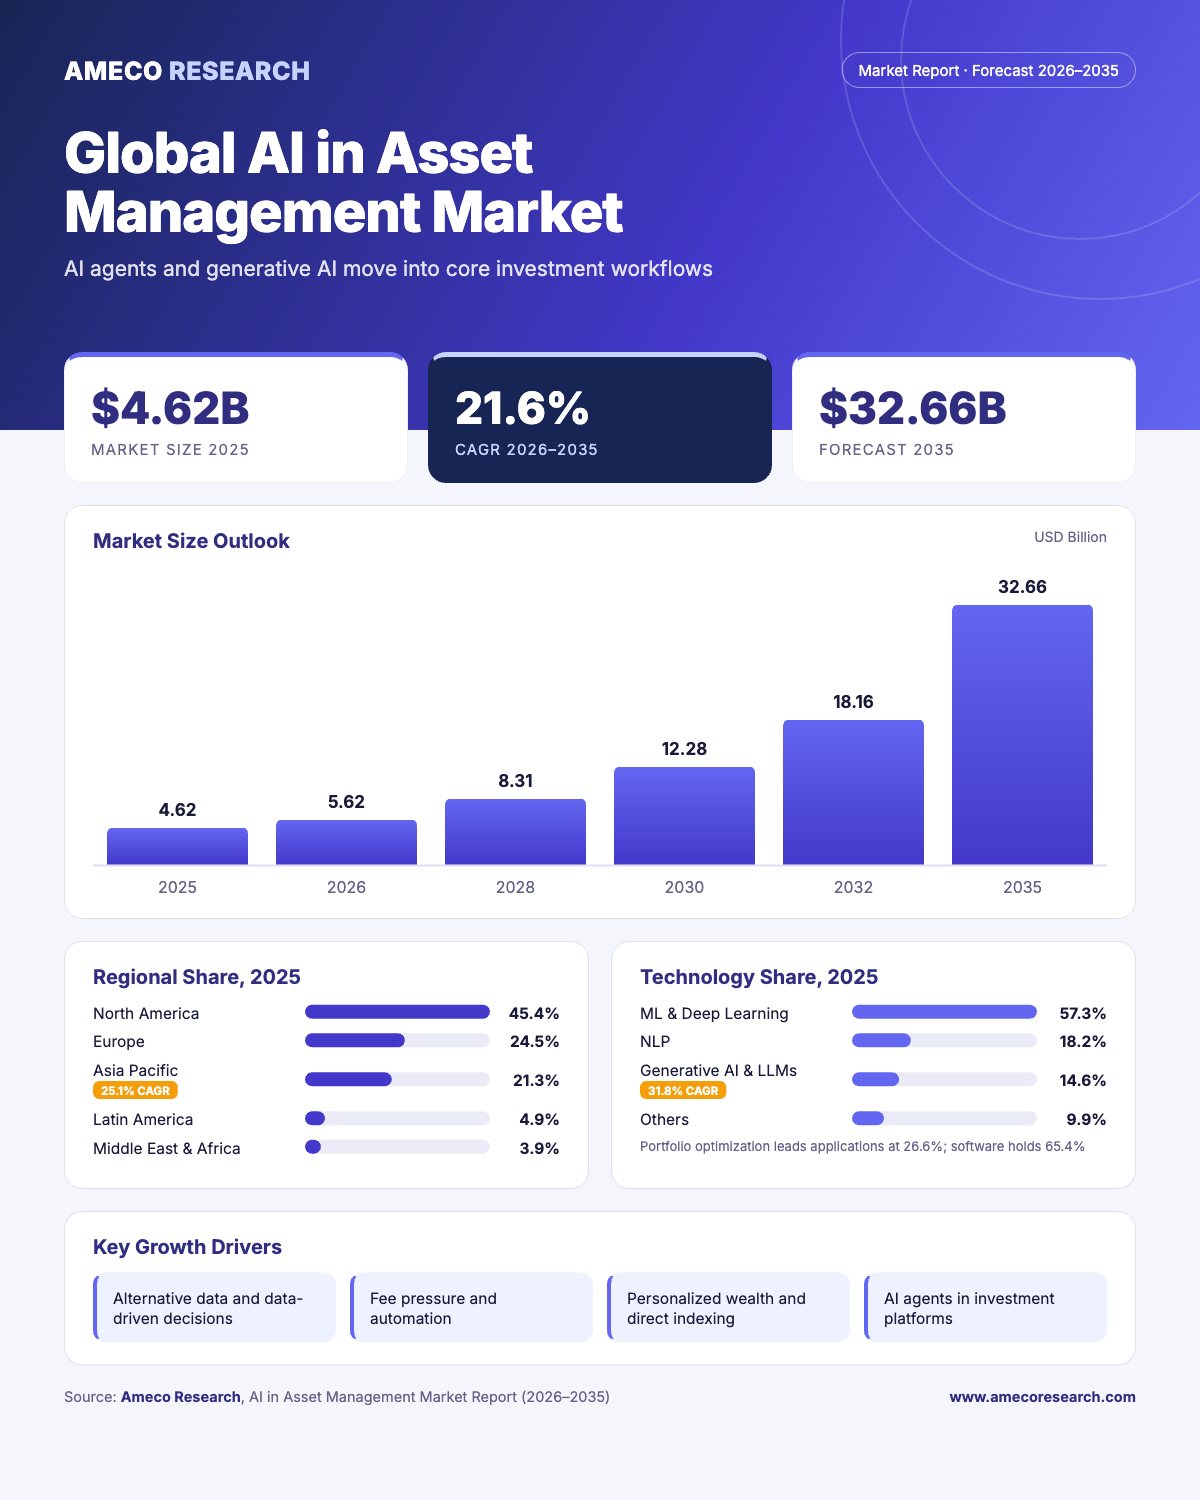
AI in asset management covers machine learning, natural language processing (NLP), generative AI, and AI agents used by investment firms to research markets, build and rebalance portfolios, manage risk, execute trades, meet compliance requirements, run back-office operations, and serve clients. The 180-page study sizes AI software, managed services, and professional services sold to asset managers, hedge funds, wealth managers, pension funds, insurers, and private market firms.
How Big Is the AI in Asset Management Market?
Ameco Research expects the market to more than double by 2030 and grow about seven-fold over the decade:
| Year | Market Size (USD Billion) |
|---|---|
| 2025 (Base Year) | 4.62 |
| 2026 | 5.62 |
| 2028 | 8.31 |
| 2030 | 12.28 |
| 2032 | 18.16 |
| 2035 | 32.66 |
Key Takeaways
- Market size 2025: USD 4.62 billion, reaching USD 32.66 billion by 2035
- Growth rate: 21.6% CAGR from 2026 to 2035
- Leading region: North America, with about 45.4% of 2025 revenue
- Fastest-growing region: Asia Pacific, at a 25.1% CAGR
- Component: Software and platforms hold 65.4%; managed services grow fastest
- Technology: Machine learning leads with 57.3%; generative AI and LLMs grow fastest at a 31.8% CAGR
- Application: Portfolio optimization and construction leads with 26.6%; client engagement grows fastest
- End user: Traditional asset managers account for 37.4%; private equity and alternatives grow fastest
What Is Driving AI Adoption in Investment Management?
Data-Driven Decisions and Alternative Data
AI lets managers analyze prices, fundamentals, news, sentiment, and alternative data such as satellite imagery, web traffic, and card transactions at a scale no human team can match, turning them into investment signals.
Fee Pressure and Efficiency
Shrinking margins and the shift to passive investing push firms to automate research, operations, and reporting. AI-driven optimization, rebalancing, tax management, and direct indexing also make customized portfolios economical at scale.
Client Personalization
Wealth managers and robo-advisors use AI to tailor advice, communication, and products to individual investors, which is why client engagement and advisory is the fastest-growing application at about a 25.7% CAGR.
AI in Asset Management Trends in 2026
- AI agents enter investment platforms: In April 2026, SimCorp launched Agent Launchpad, letting managers deploy pre-built AI agents for portfolio management, corporate actions, and risk analysis inside SimCorp One, with humans keeping final accountability.
- AI moves into core investment processes: A 2026 Mercer survey of 131 asset managers found 55% had integrated AI into at least one investment process and another 27% were piloting it. BlackRock's Asimov research platform acts as a virtual analyst for its fundamental equity team.
- Generative AI reshapes research and reporting: LLMs summarize filings and earnings calls in seconds, draft client commentaries and RFP responses, and help quants write and test code.
- Data quality is the main bottleneck: 69% of managers cited data quality or access as a material obstacle, and a 2026 BlackRock survey found 72% of investment decision-makers use eight or more platforms across the fund lifecycle.
- Rapid move to the cloud: Cloud-based AI held 43.6% of revenue in 2025 and is growing at about a 26.8% CAGR.
- Regulators set AI rules: The Monetary Authority of Singapore issued AI Risk Management Guidelines for financial institutions in October 2026, and the EU AI Act is pushing firms to strengthen model governance and explainability.
Challenges
Sensitive client and trading data must be protected as AI tools reach more systems. Data infrastructure, integration with legacy platforms, and specialist talent require significant investment. Regulators, boards, and clients need to understand why models make recommendations, and models trained on past data can fail in new market regimes. Firms also remain fully accountable for AI-supported decisions under fiduciary and conduct rules.
Segment Analysis
By Component and Deployment
Software and platforms accounted for 65.4% of revenue in 2025, professional services 22.3%, and managed services 12.3%; managed services are growing fastest at about a 24.3% CAGR as firms outsource data and AI operations. On-premises deployment held 56.4%, but cloud is expected to become the dominant model well before 2035.
By Technology
| Technology | Share (2025) | Key Highlights |
|---|---|---|
| Machine Learning & Deep Learning | 57.3% | Quant signals, forecasting, risk, and optimization |
| Natural Language Processing | 18.2% | Sentiment, news, and document analysis |
| Generative AI & LLMs (incl. AI Agents) | 14.6% | Fastest-growing at 31.8% CAGR; research, reporting, and agents |
| Others | 9.9% | Computer vision, robotic process automation, and knowledge graphs |
By Application
Portfolio optimization and construction led with 26.6% of revenue, followed by risk management and compliance (19.4%), investment research and analytics (16.8%), trading and execution (13.1%), client engagement and advisory (10.4%), and operations and others (13.7%).
By End User, Asset Class, and Firm Size
Traditional asset managers accounted for 37.4% of demand, hedge funds 17.2%, wealth managers and robo-advisors 15.8%, pension funds and insurers 13.6%, and private equity and alternatives 8.3%, the fastest-growing group at about a 24.3% CAGR. Equities were the largest asset class at 39.4%, while alternatives (16.3%) are growing fastest. Firms with more than USD 100 billion in AUM took 63.5% of revenue, but small and mid-sized firms are growing faster at about a 24.1% CAGR as cloud tools lower the cost of entry.
Regional Outlook
| Region | Share (2025) | Outlook |
|---|---|---|
| North America | 45.4% | Largest market; 19.9% CAGR; U.S. asset managers and AI vendors |
| Europe | 24.5% | 20.6% CAGR; EU AI Act and a strong fund industry |
| Asia Pacific | 21.3% | Fastest-growing at a 25.1% CAGR; China, Japan, India, Singapore, Australia |
| Latin America | 4.9% | Digital investment platforms in Brazil and Mexico |
| Middle East & Africa | 3.9% | Sovereign wealth funds and Gulf financial centers |
The U.S. is home to the world's largest asset managers, hedge funds, and wealth platforms, along with leading investment technology providers. In Asia Pacific, rapid wealth creation, booming retail investing in India and China, Japan's asset management reforms, and the fintech hubs of Singapore and Hong Kong are driving demand. European hubs in the U.K., France, Germany, Switzerland, Luxembourg, and the Nordics are adopting AI for research, ESG analysis, and operations.
Competitive Landscape
The market includes investment management platform providers, financial data and analytics firms, cloud and AI technology companies, and asset managers that build and license their own AI tools. Competition centers on data quality and coverage, integration across the investment lifecycle, generative AI and agent capabilities, model governance, and security. Companies profiled include BlackRock (Aladdin), Bloomberg, IBM, Microsoft, NVIDIA, State Street (Charles River Development), SS&C Technologies, FactSet, MSCI, SimCorp, Morningstar, Clearwater Analytics, and Palantir Technologies.
Questions on vendor coverage, pricing, or methodology? Make an Inquiry and an analyst will respond.
Opportunities Through 2035
- Personalized wealth management: AI advisors, direct indexing, and hyper-personalized portfolios for mass-affluent investors.
- Risk and compliance monitoring: Real-time surveillance, stress testing, and regulatory reporting.
- Generative AI for research: Faster analysis and broader coverage of companies and markets.
- Private markets: Digitized deal sourcing, due diligence, valuation, and portfolio monitoring.
- Small and mid-sized managers: Cloud AI platforms once affordable only to the largest firms.
Related Ameco Research coverage includes the Enterprise AI Market report, the Agentic AI Market analysis, the Machine Learning Market report, and the Online Trading Platform Market study.
Report Scope
| Report Attribute | Details |
|---|---|
| Market Size in 2025 | USD 4.62 Billion |
| Market Forecast in 2035 | USD 32.66 Billion |
| CAGR (2026–2035) | 21.6% |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2035 |
| Segments Covered | Component, Technology, Deployment, Application, End User, Asset Class, Organization Size (AUM), Region |
| Regions Covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Report Coverage | Market size and forecast, trends, drivers, restraints, opportunities, segment and regional analysis, regulatory landscape, competitive landscape, recent developments |
| Pages | 180 |
Who Should Read This Report?
- Asset managers, hedge funds, and wealth firms benchmarking AI adoption and investment priorities.
- Investment technology and data vendors sizing demand by application, technology, and region.
- Pension funds, insurers, and sovereign investors evaluating AI tools for risk and allocation.
- Private equity and venture investors tracking fintech and AI platform opportunities.
- Regulators and consultants assessing AI governance in financial services.
The report supports investment planning with ten-year forecasts, business strategy with segment growth rates, market entry with regional analysis, and competitive intelligence with vendor profiles and recent developments. Buy the AI in Asset Management Market Report for immediate access.
Conclusion
AI is becoming core infrastructure for investment firms. With revenue forecast to rise from USD 4.62 billion in 2025 to USD 32.66 billion by 2035 at a 21.6% CAGR, the managers and vendors that combine clean data, governed models, and AI agents embedded across the investment lifecycle will set the pace. Ameco Research's report gives decision-makers the data to plan that shift.
Explore the AI in Asset Management Market Report
Preview the data and methodology, ask about pricing and coverage, get the complete 180-page study, or request extra segments, country-level data, and research beyond the report’s scope.
About Ameco Research
Ameco Research is a market research and consulting firm that provides syndicated reports, customized research, and data-driven insight across industries including financial services, ICT, healthcare, energy, and automotive. Its analysts help businesses, investors, and institutions find growth opportunities and make informed strategic decisions.
Contact Us
Ameco Research
201, Vaidehi-Saaket, Baner - Pashan Link Rd, Pashan, Pune, Maharashtra 411021, India
Phone: +91 898 322 5533
E-mail: [email protected]
Website: www.amecoresearch.com